
Олександр Сич
7 April 2026
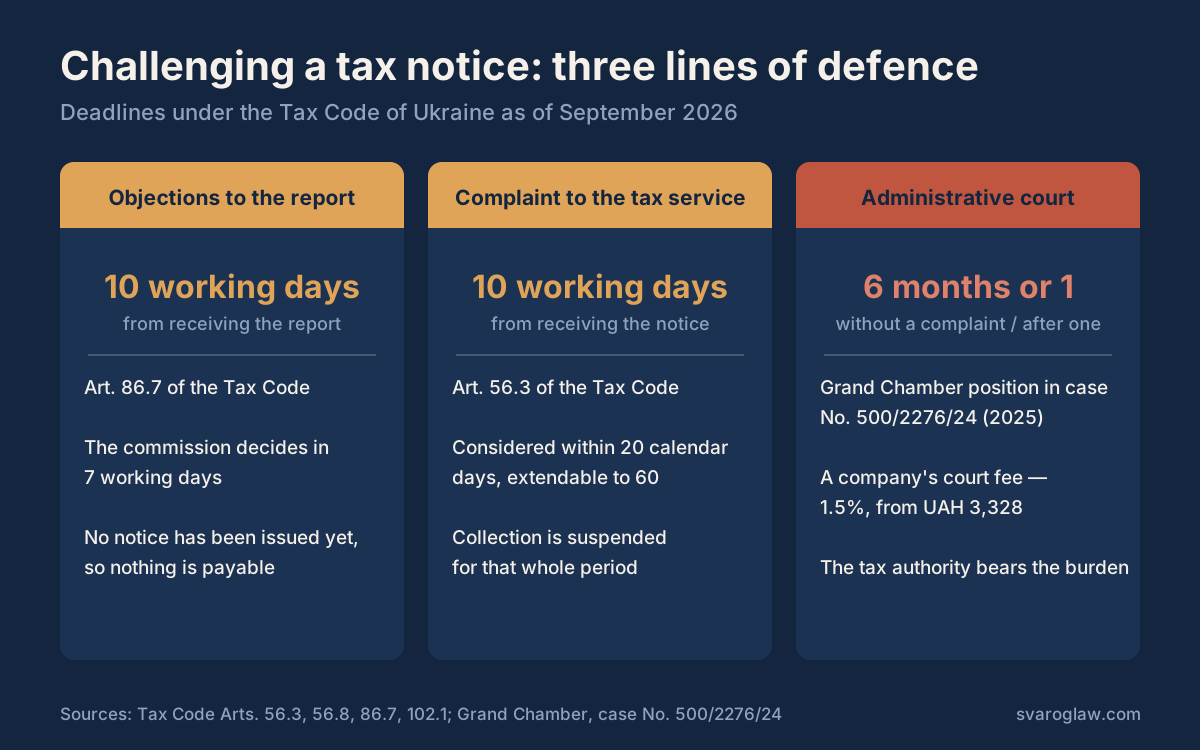
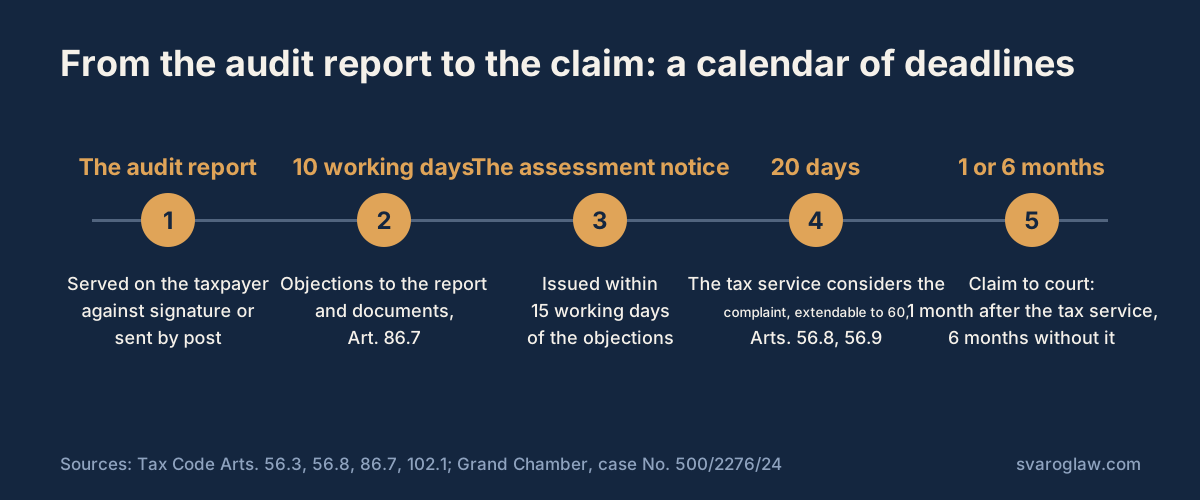
Objections to an audit report go in within 10 working days, and so does a complaint to the State Tax Service against a tax assessment notice. In July 2025, in case No. 500/2276/24, the Supreme Court’s Grand Chamber settled the point: a claim against a notice is filed within six months, and after an administrative complaint that period shortens to one month.
Ten working days is all the time the Tax Code gives a business to react after an audit report arrives, and the same again after an assessment notice is issued. A missed deadline turns the assessed sum into an agreed monetary liability, and the dispute then ceases to be about whether the assessment was lawful and becomes about how it will be collected from your accounts.
The second change not everyone has taken on board concerns the court deadline. Until 2025 it was common to file within 1,095 days, but after the Grand Chamber’s ruling the clock runs from six months, and for anyone who went through an administrative complaint first, from one. That is the stage at which a tax disputes lawyer is most often needed.
Objections to the audit report: the first line
An audit report creates no obligation to pay: it is simply the document recording the authority’s conclusions. Paragraph 86.7 of the Tax Code gives ten working days from the day after it is received to file written objections and explanations with documents. The objections commission considers them within seven working days, and the taxpayer may attend if the objections say so.
Objections are worth the effort even where the chance of persuading the tax authority is small: documents attached at that stage become part of the file, and a court sees that the taxpayer disclosed them at once rather than producing them for the hearing. The assessment notice is issued within fifteen working days of the objections being dealt with.
The administrative complaint
A complaint to the State Tax Service is filed within the ten working days following receipt of the notice, under paragraph 56.3. The authority considers it within twenty calendar days and may extend that to sixty, notifying the taxpayer in writing. If no reasoned decision is sent within the period, the complaint is treated as granted in full in the taxpayer’s favour.
The main advantage of the procedure is that enforcement stops: while the administrative complaint runs, the liability is unagreed, no money is collected and no tax lien arises. The drawback is that after a refusal only a month remains for a claim. The choice between complaining and suing directly is therefore made at the outset, and pre-trial settlement of tax disputes makes sense where the dispute is about arithmetic or documents rather than about how a provision should be read.
The court stage: what works for the taxpayer
Administrative proceedings have a rule civil ones lack: under part 2 of Article 77 of the Administrative Procedure Code the burden of proving that a decision was lawful falls on the public authority. It is the tax service that must prove the assessment was lawful, not the taxpayer who must prove innocence. In practice that is where most findings of “fictitious transactions”, built on tax data without primary documents, fall apart.
The court fee on an administrative claim of a monetary character is 1.5 % of its value for a company but no less than 3,328 UAH, and 1 % for an individual within 1,331.20 to 16,640 UAH. Filing through the Electronic Court reduces it by 20 %. How such cases are run is described on the page of our administrative cases lawyer.
| Stage | Deadline | Provision | What happens to the money |
|---|---|---|---|
| Objections to the audit report | 10 working days | para. 86.7 | no liability determined yet |
| Complaint to the tax service | 10 working days | para. 56.3 | enforcement suspended |
| Consideration of the complaint | 20 calendar days, up to 60 | paras. 56.8, 56.9 | enforcement suspended |
| Claim without an administrative complaint | 6 months | Grand Chamber, case No. 500/2276/24 | suspended by court order |
| Claim after the tax service refuses | 1 month | Grand Chamber, case No. 500/2276/24 | suspended by court order |
| Payment of an agreed liability | 10 working days | para. 57.3 | then a tax lien |
What happens if the deadline is missed
The liability becomes agreed, and the taxpayer must pay within ten working days of receiving the notice. Failing to do so turns the sum into tax arrears: the taxpayer’s property comes under a tax lien under Articles 88 and 89, and the authority gains the right to collect from the accounts by court order.
A penalty is added under Article 124: 5 % of the sum where payment is up to thirty calendar days late and 10 % beyond that, rising to 25 % for deliberate acts. Interest under Article 129 accrues at 120 % per annum of the National Bank’s discount rate for each day of delay. The overall period within which the tax authority may determine a liability at all is 1,095 days under paragraph 102.1.
What to do after an audit
- Record the date the report was received: the ten-day objection period runs from the following day.
- File the objections with copies of the primary documents and state that you intend to attend the commission.
- Once the notice arrives, choose your strategy within a day or two: a complaint suspends payment but shortens the court deadline to a month.
- If you choose the court, file the claim within six months together with an application to suspend the notice.
- Build the evidence that the transactions were real: contracts, consignment notes, acceptance certificates, bank statements, correspondence, records of goods moving and of the counterparty’s production capacity.
- After a judgment in your favour, apply to have the sum removed from the taxpayer’s integrated card and check the position in the electronic cabinet.
Typical mistakes businesses make in tax disputes
- Waiting “until the last day” and filing on the eleventh working day. The period cannot be restored administratively, and the liability becomes agreed.
- Filing a complaint “just in case” without weighing the consequences. After a refusal only a month remains for the claim, not six, and the evidence cannot always be assembled in that time.
- Producing decisive documents for the first time in court. The tax service argues they did not exist during the audit, and the court treats that against the taxpayer.
- Arguing only with the report’s conclusions and not with the figure. Even a legally sound conclusion often contains an arithmetical error that cuts the assessment by tens of per cent.
- Ignoring the tax lien once the liability is agreed. Selling liened property without the authority’s consent carries its own liability, and the buyer’s transaction is at risk.
When you do not need a lawyer
Where the issue is a penalty for registering a tax invoice late and the lateness is obvious, it is cheaper to pay and move on: the prospects of a dispute are close to nil. Objections to a report can likewise be filed alone where the inspector’s error is arithmetical and one document settles it. Legal help pays for itself where the assessment runs into hundreds of thousands, where the conclusion rests on fictitious transactions through a chain of counterparties, or where criminal proceedings under Article 212 of the Criminal Code have appeared alongside the notice.
Questions and answers
How long is there to challenge a tax assessment notice
Ten working days for a complaint to the tax service, from the day after the notice is received. For going to court without an administrative complaint, six months.
Which is better: a complaint to the tax service or going straight to court
A complaint suspends payment and costs nothing, but after a refusal only a month remains for a claim. A direct claim gives six months to prepare, but needs an application to suspend the notice.
Does a complaint stop collection
Yes, filing a complaint stops collection. While the administrative challenge runs, the liability counts as unagreed, so the tax service may neither collect the sum nor apply a tax lien.
What if the tax service does not answer in time
The complaint is treated as granted in full in the taxpayer’s favour. The period for considering it is twenty calendar days and may be extended to sixty with written notice.
What is the court fee in a tax dispute
For a company, 1.5 % of the value of the claim but no less than 3,328 UAH in 2026; for an individual, 1 % within 1,331.20 to 16,640 UAH. Filing through the Electronic Court gives a 20 % discount.
Who proves that the assessment was lawful
The tax authority does. Part 2 of Article 77 of the Administrative Procedure Code places the burden of proving a decision lawful on the public authority.
How long does a tax dispute take in court
The first instance usually takes six months to a year, with an appeal adding three or four months. It grows longer where a forensic accounting report is ordered.
For what period can the tax authority assess
For 1,095 days following the last day of the deadline for filing the return, under paragraph 102.1. In certain cases, including where no return was filed, that period does not apply.
Can the order appointing an audit be challenged
It can, but it is more effective before the audit begins. Once the audit is over, courts assess procedural defects in the appointment together with the substance of the assessment.
What does handling a tax dispute cost
A consultation starts at 1,500 UAH, a written legal opinion and the preparation of procedural documents at 5,000 UAH, and full handling of an administrative case at 30,000 UAH.
Sources
- Tax Code of Ukraine, paras. 56.3, 56.8, 56.9, 57.3, 86.7, 102.1, Arts. 88, 89, 124, 129
- Administrative Procedure Code of Ukraine, Art. 77
- Law of Ukraine “On Court Fees”
- Unified State Register of Court Decisions: Supreme Court Grand Chamber ruling in case No. 500/2276/24
- State Tax Service of Ukraine
- Taxpayer’s electronic cabinet
Tax dispute representation with Svarog
We analyse the audit report before the notice is issued, prepare the objections and the complaint to the tax service, run the case in the administrative court and see the tax lien lifted. If what you need is a challenge to a tax assessment notice, we will assess the prospects at the first consultation; the rates are in our legal service prices.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00