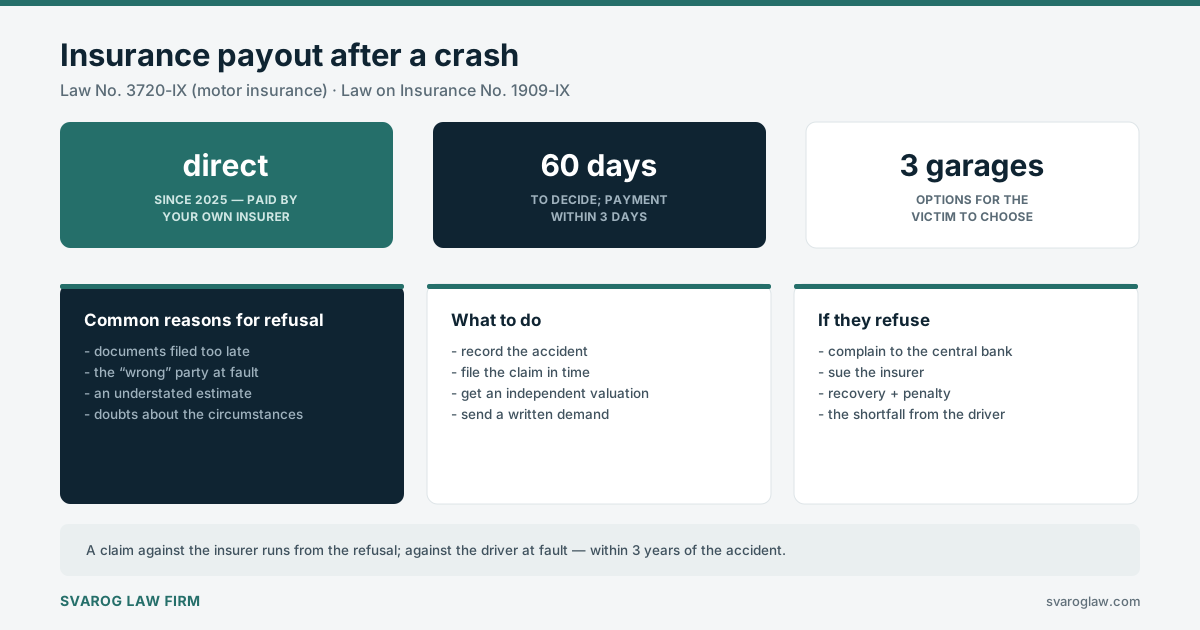
Paying out on an insurance claim is the insurer’s obligation under the contract and the law. Insurance is governed by the Law of Ukraine “On Insurance” No. 1909-IX, and motor claims by the Law “On Compulsory Civil Liability Insurance of Owners of Land Vehicles” No. 3720-IX, in force since 1 January 2025. It made direct settlement mandatory for all motor insurers: where only property is damaged, the victim claims from their own insurer rather than the other driver’s.
Even so, refusals and understated payouts remain commonplace. The insurer “sees no grounds”, cites late documents, disputes who was at fault, understates the repair estimate, deducts depreciation (which the current motor insurance rules forbid), or simply stays silent beyond the deadlines. Comprehensive policies add their own grounds: “improper storage”, “breach of the policy terms”, “late notification”. Most of this is the insurer’s negotiating position, and it can and should be challenged.
We establish the real reason for the refusal or the shortfall, obtain an independent valuation and send a demand, and if the insurer does not respond we complain to the National Bank, which supervises the insurance market, and recover the payout in court together with the penalty for the delay.
The deadlines and caps the dispute runs from
The insurer decides on payment within 60 days of receiving the complete file, and in complex cases where the circumstances of the accident are still being established that can extend to 90 days. Payment follows the decision immediately, and the law provides a penalty for each day of delay.
Anything above the cap is recovered from the driver at fault in a separate action: that is covered on the page about compensation after a road accident, and the exact loss is evidenced by an independent damage assessment.
Why insurers refuse or underpay
The typical grounds we deal with:
- “missed deadlines” for notifying or filing documents — often arguable or excused by good reasons;
- doubt about the circumstances of the accident or about who was at fault;
- an understated repair estimate by the insurer’s own appraiser;
- deduction of depreciation, which the current motor insurance rules do not allow;
- on comprehensive policies — “breach of the policy terms”, exclusions from cover;
- delay: the insurer does not decide within the statutory period.
What the new motor insurance rules give you
Mandatory direct settlement makes life simpler for the victim: for property damage you deal with your own insurer, which is easier to talk to, and which must offer you repair options. Simplifying the procedure has not ended arguments about the figure: it is at the estimate stage that payouts are most often cut. So accept the first sum offered only after an independent check, and sign a “no further claims” document only when that sum suits you.
What the court examines in a dispute with an insurer
The court looks at four things: whether the event is an insured event under the policy and the law, whether the insurer was notified properly, what the real loss is, and whether the insurer paid late. The wording of the refusal is not decisive — what matters is whether it is supported by the policy, the insurance rules and the evidence.
The loss is proved by a valuer’s report or a court-appointed vehicle valuation. The insurer’s estimate is only one piece of evidence, and it loses to a report prepared with the car inspected and the damage photographed. When the insurer sees such a document and a penalty calculation, the case often ends in a further payment before judgment: losing costs more than paying voluntarily.
How we handle insurance disputes
- we analyse the policy, the insurance rules and the written ground of refusal;
- we arrange an independent valuation where the payout is too low;
- we prepare a reasoned demand to the insurer with the shortfall calculated;
- if it refuses or stays silent, we complain to the National Bank and prepare the claim;
- in court we recover the payout together with the penalty for late payment;
- where necessary we recover the balance above the insurer’s cap from the driver at fault.
What people risk by going it alone
Money is most often lost at two points: signing a “no further claims” document after receiving an understated sum, and accepting a refusal “for lateness” as final when the deadline could be restored or the ground itself challenged. Then come the evidence mistakes — without an independent valuation there is nothing to set against the insurer’s estimate, and without a timely claim limitation runs out. It runs from the day the person learned of the breach (Art. 261 of the Civil Code), which is usually the date of the refusal or the expiry of the decision period; for penalty claims the period is one year (Art. 258).
A case from our practice
In 2025 a car owner came to us who had been awarded about 46,000 UAH under direct settlement, while the garage had quoted nearly twice as much. The insurer’s estimate deducted depreciation and left out part of the hidden damage found on dismantling. We commissioned an independent valuation with the car inspected, filed a demand with the shortfall and the penalty calculated, and complained to the National Bank. The insurer paid the difference, plus the cost of the valuation, before any court hearing — about three months after the client came to us. Our fee at that stage was 10,000 UAH. (details changed)
Cost of services (insurance payouts)
Court fees (2026): a claim against an insurer is a monetary one, so an individual pays 1 % of its value, but not less than 1,331.20 and not more than 16,640 UAH; filing through the Electronic Court multiplies the rate by 0.8. The independent valuation is paid separately. Everything that follows a crash is handled by our road accident lawyer; where there are injuries, a lawyer for Art. 286 cases works alongside.
Calculate the court fee for a claim against the insurer
The value of the claim is the gap between the real loss and the payout, plus the penalty for the delay.
Questions and answers (insurance payouts)
The driver at fault had no motor policy. Who pays?
Harm to life and health is then compensated by the Motor Transport Insurance Bureau of Ukraine from the victims’ protection fund, while damage to the car is recovered from the driver directly in court. The court needs the documents from the scene, the valuer’s report and proof that no valid policy existed.
Can the car be repaired before the insurer inspects it?
No, not until the insurer has inspected the damage or the time allowed for the inspection has passed. A repaired car leaves the expert nothing to examine, and that is the commonest reason a court cannot establish the real loss. The exception is hidden damage found on dismantling: it is recorded in a separate garage report with photographs.
How long does a case against an insurer take?
Usually from six months, and the main factor is the court-appointed vehicle valuation: the proceedings are stayed while it is carried out. If the insurer does not dispute how the accident happened and the argument is only about the figure, the case moves faster, and the further payment often arrives before judgment.
Can the lawyer’s fees be recovered from the insurer?
Yes, the cost of professional legal assistance is apportioned between the parties by the outcome (Arts. 137, 141 of the Civil Procedure Code). The engagement letter, a detailed description of the work and proof of payment are filed with the court, which assesses whether the sum is proportionate to the complexity. The court fee and the expert report are also compensated by the losing party.
Do I have to come to Kyiv to run the dispute?
No. The engagement letter and the power of attorney are done remotely, the claim is filed through the Electronic Court, and hearings can be attended by video. Attendance in person is needed only for the appraiser’s inspection, which takes place wherever suits you.
Contact a Svarog insurance disputes lawyer
Send us the policy, the accident documents and the insurer’s written reply. We will assess whether the refusal or the shortfall is lawful, calculate what is owed plus the penalty, and take the dispute on. If a valuation is needed, or the balance has to be recovered from the driver, we do that within the same case. The area is handled by our road accident lawyer.