Pre-court settlement of tax disputes has a specific form in the Tax Code: an administrative appeal against a tax notice-decision to a higher tax authority. It is the only way to challenge an assessment without a fee and without a claim, and while the appeal is pending the monetary liability remains unagreed: no tax debt arises. But the procedure has a flip side that shapes the whole strategy: after the tax service refuses, you have one month to go to court instead of the six you would have had if you had gone straight there para. 56.19 of the Tax Code; that is how the Supreme Court reads the provision in its judgment of 26 November 2020 in case No. 500/2486/19.
So the decision to “try to settle with the tax office first” should not be automatic: the choice depends on the strength of the arguments, the sum at stake and the tax service’s position in similar disputes.
How the appeal is filed
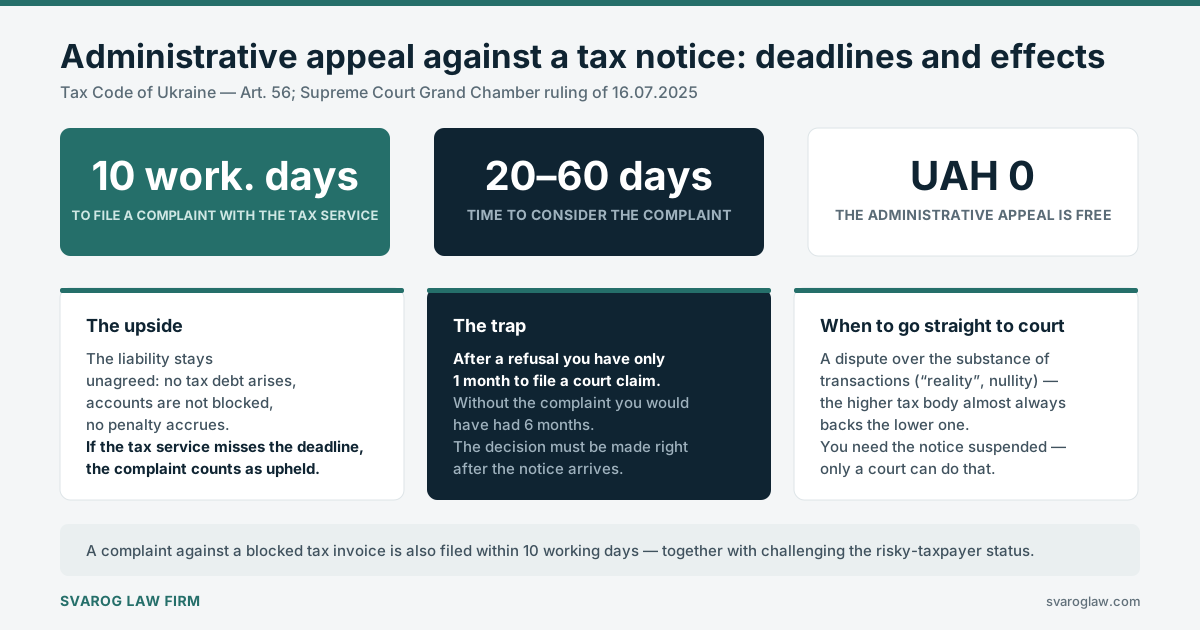
The appeal goes to the higher tax authority (for notices issued by territorial offices, that is the State Tax Service of Ukraine) within 10 working days following the day the notice was received para. 56.3, Art. 56 of the Tax Code. Miss it, and the right of administrative appeal is lost; only the court remains, and on a different clock. A copy of the appeal goes at the same time to the office that issued the notice para. 56.5.
The appeal is considered within 20 calendar days para. 56.8; the head of the authority may extend that to 60 days, notifying the taxpayer in writing before the twenty-day period ends. If a reasoned decision is not sent in time, the appeal is deemed fully allowed in the taxpayer’s favour and the notice cancelled para. 56.9. We keep track of that date ourselves.
The taxpayer has the right to take part in the hearing of the appeal in person: to file additional documents and to give oral explanations.
What the appeal gives you: an unagreed liability
While the administrative appeal is pending, the monetary liability is treated as unagreed. That means:
- No tax debt arises, and therefore no tax lien.
- Accounts and property are not frozen.
- Penalties and interest do not accrue on the amount in dispute.
- The taxpayer does not appear in the register of taxpayers with tax debt.
The liability becomes agreed on the day the administrative appeal procedure ends para. 56.17, and from that day there are 10 working days to pay if you have not filed a claim.
Deadlines that are not restored: one month for the claim
The deadline for a claim to the administrative court depends on whether you appealed:
6 months from the day the notice was received.
1 month from the day the decision on the appeal was received (or from the day the 20- or 60-day period for deciding it should have expired).
Here is how it looks on a calendar: the notice arrives on 12 February, the appeal is filed on 24 February, the review period is extended, the refusal arrives on 20 April. The claim must be filed by 20 May. A taxpayer who turns up on 25 May thinking “I still have four months” is refused leave to proceed. So the decision whether to appeal is taken as soon as the notice arrives, on the footing that only a month will be left for court afterwards, and we prepare the claim in parallel with waiting for the reply.
When to go to the tax service first, and when straight to court
The breach is obvious and formal: an arithmetic error, a breach of audit procedure, an assessment beyond the 1,095-day limitation period Art. 102 of the Tax Code. A higher authority will sometimes concede such points without a fight. You need time: it matters to the company that its accounts are not frozen right now. The sum is small and the cost of litigation would be out of proportion.
The dispute goes to the substance of the transactions: “unreal business operations”, void transactions. Here the tax service almost always backs its territorial office. The sum is large, and a month lost on an appeal that was always going to fail creates a needless risk of missing the deadline. You need interim relief: only a court order can suspend a tax notice Art. 150 of the Code of Administrative Procedure.
Administrative appeal where tax invoices are blocked
The same logic, only the deadlines are tighter. An appeal against a commission’s refusal to register a tax invoice is filed within 10 working days of the decision para. 56.23 of the Tax Code, Procedure No. 1165. At the same time we challenge the decision classifying the taxpayer as risky, otherwise the next invoices will be blocked too.
A case from our practice
In 2025 the owner of a building materials company came to us after a documentary audit: a notice assessing 620,000 UAH of VAT and penalties on transactions with two suppliers the tax office called “risky”. Part of the assessment covered a period beyond the 1,095 days, and for the remaining transactions the client had consignment notes, certificates and bank payments. We filed the appeal on the ninth working day and prepared the claim in parallel. The State Tax Service cancelled the notice for the time-barred period (about 180,000 UAH) and refused the rest; we filed the claim for the balance on the 12th day after receiving the decision. The pre-court stage took two months and cost the client about 10,000 UAH (details changed).
How we work
- We analyse the notice and the audit report, looking for procedural breaches and for weaknesses on the substance.
- We set the strategy: appeal or go straight to court, with every following deadline calculated.
- We prepare the appeal with the full evidence and the calculations.
- We represent the taxpayer in person at the hearing of the appeal.
- We track the review deadlines and record the failure to act if the tax service does not answer in time.
- We prepare the claim in advance, so that a refusal does not eat the one-month deadline in drafting from scratch.
Cost of services
The administrative appeal is free: there is no fee for filing it. If the matter does go to court, the court fee in 2026 for a company’s claim to set aside a tax notice is 1.5 % of the amount assessed, but not less than 3,328 and not more than 33,280 UAH; for a sole trader 1 %, from 1,331.20 to 16,640 UAH; through the Electronic Court the rate is multiplied by 0.8.
Full price list · Challenging tax notices-decisions
Questions and answers (Administrative appeal against a tax notice)
The deadline for the appeal has been missed. Can it be restored?
Only on the grounds in para. 102.6 of the Tax Code: being outside Ukraine or in captivity, force majeure and the other circumstances on the exhaustive list, and only on a written application with evidence. If there are no such grounds, what remains is a claim to the court within six months of receiving the notice.
Can the appeal be filed through the Electronic Cabinet?
Yes, with a qualified electronic signature; the date of dispatch is recorded automatically. The delivery receipt removes any argument about the date of filing.
Can the appeal be supplemented after it is filed?
Yes. Until the decision is taken the taxpayer may provide additional documents and explanations, including at the hearing in person. That matters where documents from counterparties or the bank turned up after the audit.
Can the State Tax Service’s decision on the appeal itself be appealed administratively again?
No. A decision of the central authority on an appeal is final and not subject to further administrative appeal (para. 56.10 of the Tax Code); after that it is only the court, within a month.
What happens to the liability if the tax service refuses and I decide not to litigate?
The liability becomes agreed on the day the appeal ends, and must be paid within 10 working days. After that a tax debt arises, a tax lien attaches and interest starts to run.
Can the appeal be handled remotely if the company is not in Kyiv?
Yes. We file the appeal through the Electronic Cabinet, attend the hearing as your representative under a power of attorney, and file the claim through the Electronic Court.
Contact a Svarog lawyer about pre-court settlement of tax disputes
Send us the tax notice and the audit report. We will calculate the deadlines and tell you whether it is worth appealing to the tax service, or better to prepare a claim straight away with the full six-month period intact.