
Олександр Сич
4 April 2026
Recourse factoring is funding against the assignment of a monetary claim in which the risk of non-payment stays with the supplier: the factor pays out 70–90 % of the invoice within days, and if the buyer fails to pay on time it returns the claim to the client and takes back the money advanced. From 30 July 2026 only an institution licensed by the National Bank may act as a factor.
On 30 July 2026 the Law of Ukraine “On Factoring” No. 4466-IX took effect, and a market that had lived for thirty years on a handful of Civil Code articles acquired rules of its own: state registration of assignments of monetary claims, priority by the time of that registration, and separate requirements for factors. For a business shipping goods on 30 to 90 days’ credit, that changes not the idea of factoring but how the counterparty is checked and the paperwork done.
The commonest variety in Ukraine is recourse factoring, where a finance company advances money against an invoice but does not take on the risk that the buyer will not pay. It is cheaper than non-recourse factoring and easier to obtain than a bank loan, but it puts responsibility for the debtor back on the supplier. Below: how the risks fall, what it costs, what exactly the new law changed, and where businesses most often lose money.
What factoring is and how it differs from a loan
The factoring contract is described in Articles 1077–1086 of the Civil Code: one party (the factor) transfers, or undertakes to transfer, money to the client for a fee, and the client assigns to the factor its monetary claim against a third party, the debtor. The subject may be a claim already due for payment or a future claim for goods not yet shipped.
What separates factoring from a loan is where the money comes back from. A bank lending money looks at the security and the borrower’s finances; a factor looks first at the payment record of the client’s debtors. That is why bank factoring is often available to companies a bank refused a loan for want of property to pledge, but which supply retail chains or state buyers whose payments are predictable. One further point of reference: since 28 August 2025 the Commercial Code has had no force under Law No. 4196-IX, so the parties’ contractual relations are governed solely by the Civil Code and specific legislation.
With and without recourse: who carries the risk
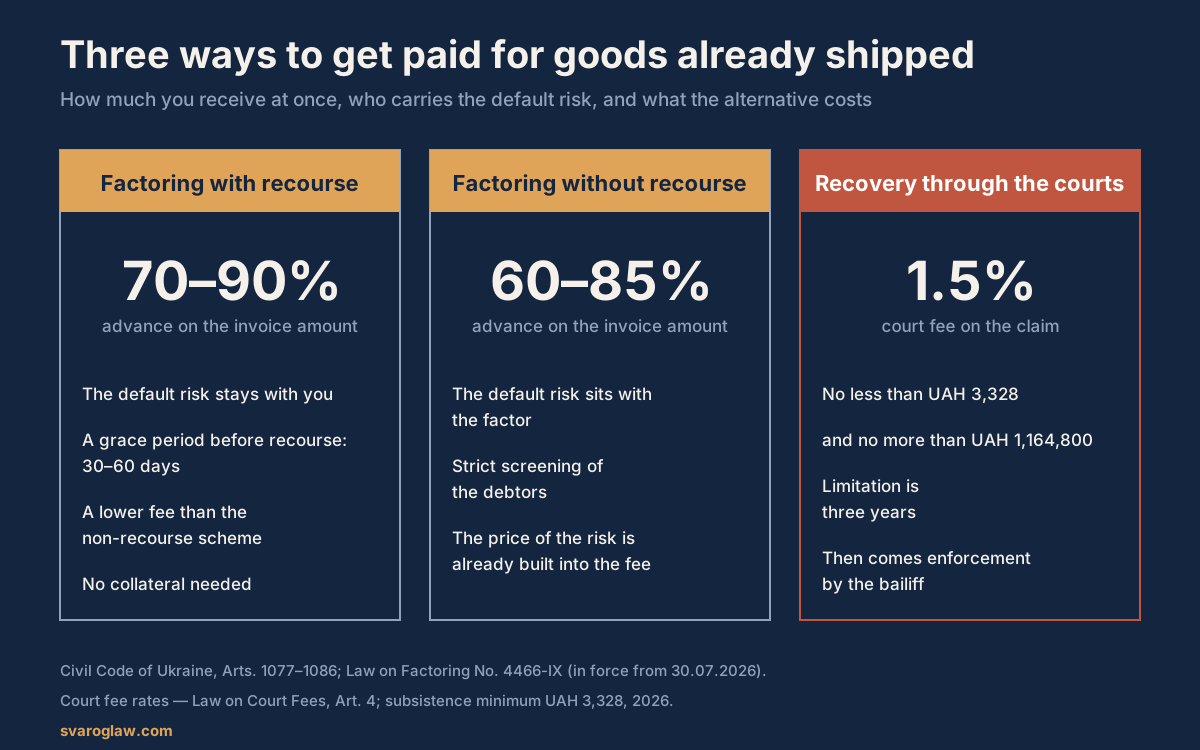
Recourse is the factor’s right to turn the claim back on the client where the debtor has not paid by the agreed date. In practice the contract sets a grace period, usually 30 to 60 days after the due date, and only then does the factor demand the advance back with its commission. Non-recourse factoring takes that risk off the supplier, but the factor prices it in and is far more selective about debtors.
The choice between the two turns on how sure you are of your buyers. If you supply three large chains with a ten-year payment history, recourse almost never bites and paying to insure the risk makes no sense. If the debtors are new or small, cheaper recourse factoring can turn into a double blow: the goods are shipped, the money goes back to the factor, and the debt has to be chased yourself.
| Term | Recourse factoring | Non-recourse factoring |
|---|---|---|
| Who carries the non-payment risk | The supplier (the client) | The factor |
| Size of the advance | Usually 70–90 % of the invoice | Usually 60–85 % of the invoice |
| Cost of the service | Lower, reflecting the lesser risk | Higher, with the risk priced in |
| Requirements on the debtor | Moderate; the client’s standing matters more | Strict, with the payment history checked |
| If the debtor does not pay | The factor returns the claim to the client | The factor pursues the debt itself |
| Who it suits | Suppliers with steady buyers | Moving into new or riskier debtors |
What the Factoring Law changed from 30 July 2026
Law No. 4466-IX was passed on 3 June 2025 and came into operation a year after taking effect, on 30 July 2026. It brings the UNIDROIT Model Law on Factoring into Ukrainian law and solves the problem that made banks wary of lending against receivables for years: the impossibility of checking whether the same claim had already been assigned to someone else.
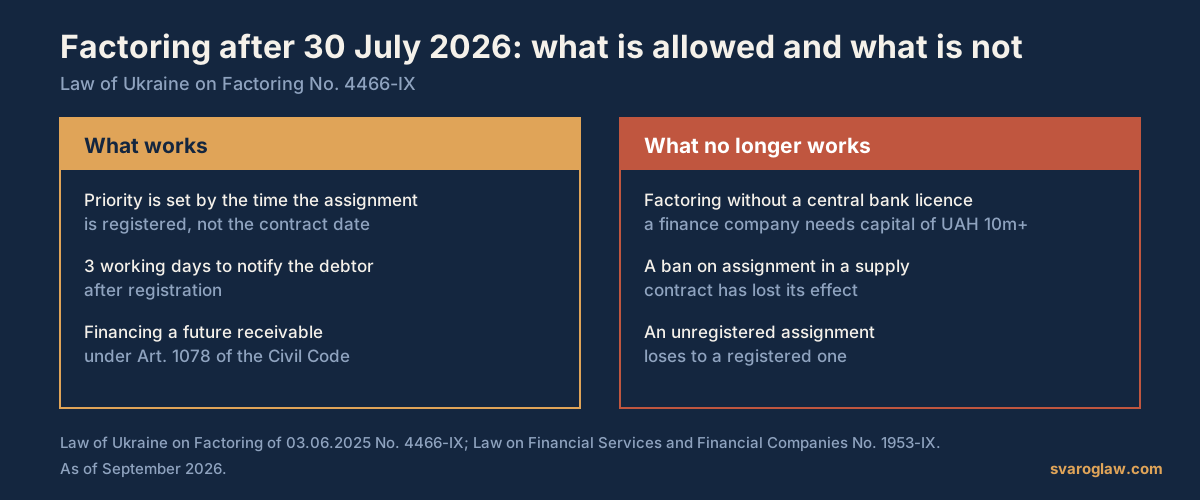
The main innovation is state registration of the assignment of a monetary claim. Priority is determined by the time of registration, regardless of when the factoring contract was made or when the claim arose, and a registered assignment prevails over an unregistered one. The second change concerns contractual clauses: terms of the underlying contract prohibiting assignment lose their force, so a buyer can no longer block factoring with a single clause. The law also separated trade factoring from operations involving financial debt and required the debtor to be notified within three working days of registration.
Who may act as a factor and what the service costs
Factoring services may be provided by banks and by finance companies licensed by the National Bank under the Law “On Financial Services and Finance Companies” No. 1953-IX. The capital requirements have been tightened: a finance company providing a single service, factoring included, must hold own capital of at least 10 million UAH. A counterparty’s licence can be checked in the National Bank’s register of financial institutions, and that is worth doing before signing rather than after the money moves. If you are planning to enter this market yourself, the timeframes and requirements are set out on the page about registering a factoring company.
The cost has two parts: a funding charge accruing for each day the money is used, and a commission for servicing the claim. In weighing the benefit, compare it not with a deposit rate but with the alternative: recovering the debt in the commercial court costs 1.5 % of the claim in court fees, but no less than 3,328 UAH and no more than 1,164,800 UAH, plus several months of litigation and enforcement. Paragraph 196.1.5 of the Tax Code takes assignment and factoring operations outside VAT where the debt is in currency values, so the tax burden on the operation itself is minimal.
Entering a factoring contract, step by step
- Check the factor in the National Bank’s register of financial institutions and obtain a copy of the licence. A contract with an unlicensed party is held invalid by the courts, and the money has to be returned.
- Gather the documents behind the claim: the supply contract, delivery notes, consignment documents, reconciliation statements. A factor funds only confirmed and undisputed debt.
- Agree the terms in the contract: the advance, the length of the grace period before recourse applies, the funding charge, the commission and how the debtor is notified.
- Wait for the assignment to be registered. It is the moment of registration that gives your factor priority over other creditors, so funding without it is risky for both sides.
- Check that the debtor is notified within three working days of registration. Until they are, the debtor may lawfully pay the old creditor, and that payment will count as good.
- Track the payment to the end of the grace period. If the debtor goes quiet, prepare the pre-action demand in advance: once the claim comes back under recourse, recovery is yours, and pre-action settlement of commercial disputes is cheaper than court.
Typical mistakes
- A contract with an unlicensed “factor”. An assignment to someone without financial institution status is treated by the courts as disguised factoring and the transaction is held invalid, leaving the client with neither the money nor the claim.
- Ignoring notice to the debtor. If the debtor never received notice of the assignment, they lawfully pay the previous creditor, and the factor will demand that sum from the client.
- Factoring a disputed receivable. Where the buyer has complaints about the goods, they will raise them with the factor too; the claim comes back under recourse along with the funding charge already accrued.
- An unagreed grace period. A contract under which recourse bites the day after the due date turns factoring into an expensive few-week loan.
- Assigning the same claim twice. Now that registration has begun, priority goes to whoever registers first, and the second factor will pursue its losses from the client.
When you do not need a lawyer
If you work with a large bank on its standard factoring form, there is a single long-established debtor and the funding is modest, legal support for every shipment is overkill. Banks in such cases handle the registration and notices themselves, and their contract forms have already been reviewed by the National Bank. A lawyer is needed where the factor is a non-bank company using its own wording, where the claim is secured by a pledge or a guarantee, where the debtor is already late, or where you are assigning a future claim. Reviewing the contract fits within a written legal opinion from 5,000 UAH; indicative figures are on the page of legal service prices.
Questions and answers
What is factoring in plain terms
It is selling the right to an unpaid invoice to a finance company. The supplier gets most of the sum at once, the factor waits for the buyer to pay and keeps a commission for the wait.
How does recourse factoring differ from non-recourse
Under the recourse scheme the debtor’s non-payment risk stays with the supplier: if the buyer does not pay, the factor hands the claim back to the client. Non-recourse factoring moves that risk to the factor, and so costs more.
What percentage does the factor pay out straight away
The advance is a matter of contract and is usually 70–90 % of the invoice under a recourse scheme. The rest, less the commission, reaches the client once the debtor has paid.
Can an ordinary company act as a factor
No. Only banks and finance companies licensed by the National Bank may provide factoring services, and a finance company offering a single service must hold own capital of at least 10 million UAH.
Is the debtor’s consent needed for factoring
Consent is not needed; notice is. Law No. 4466-IX requires the debtor to be notified within three working days of the assignment being registered, and contractual bans on assignment have lost their force.
Is a factoring operation subject to VAT
Paragraph 196.1.5 of the Tax Code takes assignments of claims and factoring operations outside the scope of VAT where the debt is in currency values. A particular operation is worth checking with a tax adviser.
What if the debtor does not pay the factor
Under a recourse scheme the factor demands the advance back from the client once the grace period expires. The claim against the debtor returns to the client, and recovery falls to them, usually through the commercial court.
Can a claim be assigned if the supply contract forbids it
Yes. Since the Factoring Law took effect, terms of the underlying contract prohibiting the assignment of a monetary claim have no legal force, and a buyer cannot block factoring with such a clause.
What does recovering the debt in court cost instead
The court fee on a monetary claim in the commercial court is 1.5 % of its value, but no less than 3,328 UAH and no more than 1,164,800 UAH. Add the cost of legal help and the time enforcement takes.
Does factoring suit work with state buyers
Yes; predictable budget payments make such receivables attractive to factors. Just check whether the contract contains special restrictions on changing creditor, and allow for treasury payment timelines.
Sources
- Civil Code of Ukraine, Arts. 1077–1086 — zakon.rada.gov.ua/laws/show/435-15
- Law of Ukraine “On Factoring” No. 4466-IX — zakon.rada.gov.ua/laws/show/4466-20
- Law of Ukraine “On Financial Services and Finance Companies” No. 1953-IX — zakon.rada.gov.ua/laws/show/1953-20
- Tax Code of Ukraine, paragraph 196.1.5 — zakon.rada.gov.ua/laws/show/2755-17
- National Bank of Ukraine register of financial institutions — bank.gov.ua
Recourse factoring with Svarog
We check the factor’s licence and its contract terms, negotiate the grace period and the way the debtor is notified, handle the registration of the assignment, and represent the client in disputes once a claim has come back under recourse. If you are still weighing factoring against a loan or litigation, start with a consultation and a written opinion on the particular receivable.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00