
Олександр Сич
3 April 2026
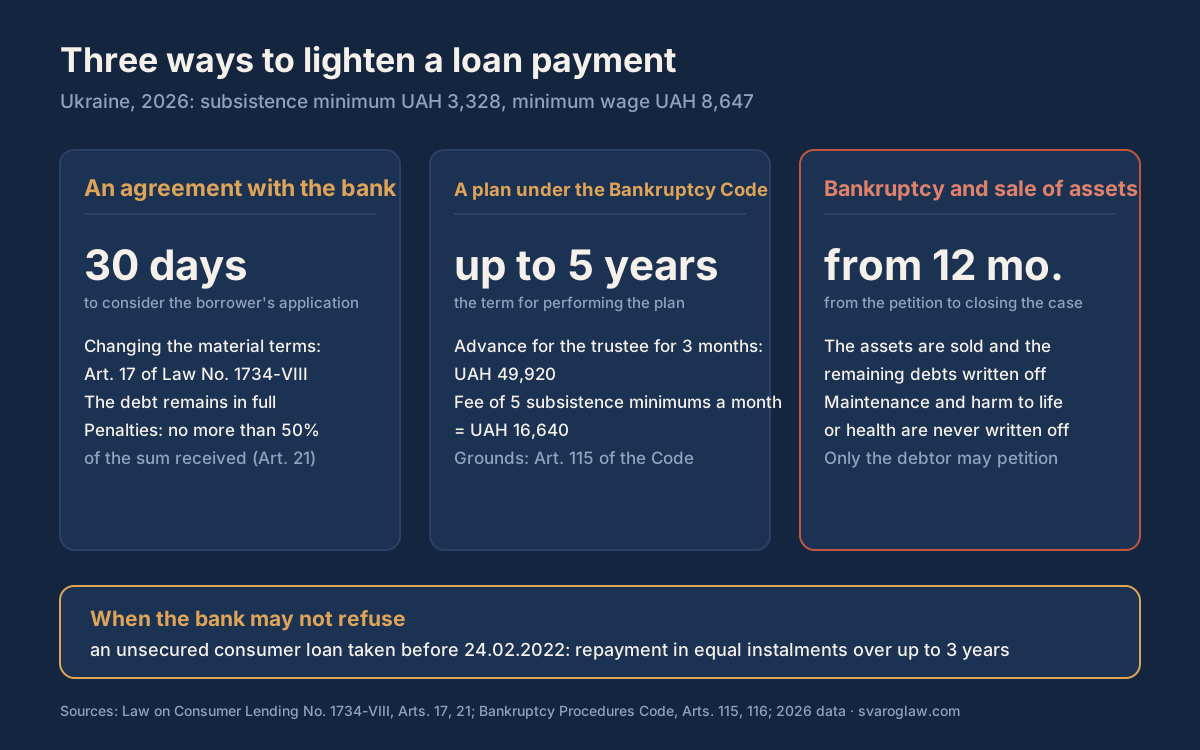
Restructuring a loan means changing the essential terms of the contract under Article 17 of the Law “On Consumer Lending”: the term, the schedule or the instalment. The bank considers the borrower’s application within thirty days and is not obliged to agree. If it refuses, what remains is court restructuring under the Code on Bankruptcy Procedures, with a plan of up to five years — but that requires an advance of 49,920 UAH.
In 2026 the minimum wage is 8,647 UAH and the subsistence minimum for working-age people 3,328 UAH, and every cost facing a borrower who wants to lighten the payment lawfully is calculated from those figures. Restructuring does not write off the debt: it moves it in time, changes the schedule and usually increases the total paid.
So the decision must rest on arithmetic, not on the wish to buy a few calm months. There are two different mechanisms with different consequences: contractual restructuring, which a bank grants at its own discretion, and court restructuring, which runs inside insolvency proceedings and affects every creditor at once.
What the law means by restructuring
Article 17 of the Law “On Consumer Lending” defines restructuring as amending the essential terms of the contract so that the conditions or the manner of repaying change. That may be extending the term, changing the schedule, cutting the monthly instalment and moving the principal to the end, or partly forgiving accrued penalties. The mechanism rests on Article 651 of the Civil Code: a contract is changed by agreement, and the bank may refuse without giving reasons.
A separate case is where the parties end the old obligation entirely and enter a new one. That is novation under Article 604, and it has an important consequence: along with the old obligation, guarantees and other security end unless the guarantor consented to the new terms. Banks know this and usually draw up a supplemental agreement rather than a new contract.
For some borrowers restructuring is not a matter of the bank’s goodwill. The final and transitional provisions of the Law “On Consumer Lending” provide for compulsory restructuring of unsecured consumer loans made before 24 February 2022, where there is no judgment and no open enforcement proceedings. The debt is then repaid in equal instalments over three years, or to the end of the original term if that is longer.
Bank restructuring: what is actually on offer
A bank assesses not how hard your situation is but how likely it is to get its money back. So the real offers come down to a few standard structures: payment holidays with interest only, extending the term and cutting the instalment, capitalising the arrears into the principal, moving from an annuity schedule to a classic one. The first remains the commonest — and the most expensive in the long run, since the principal does not fall at all in the meantime.
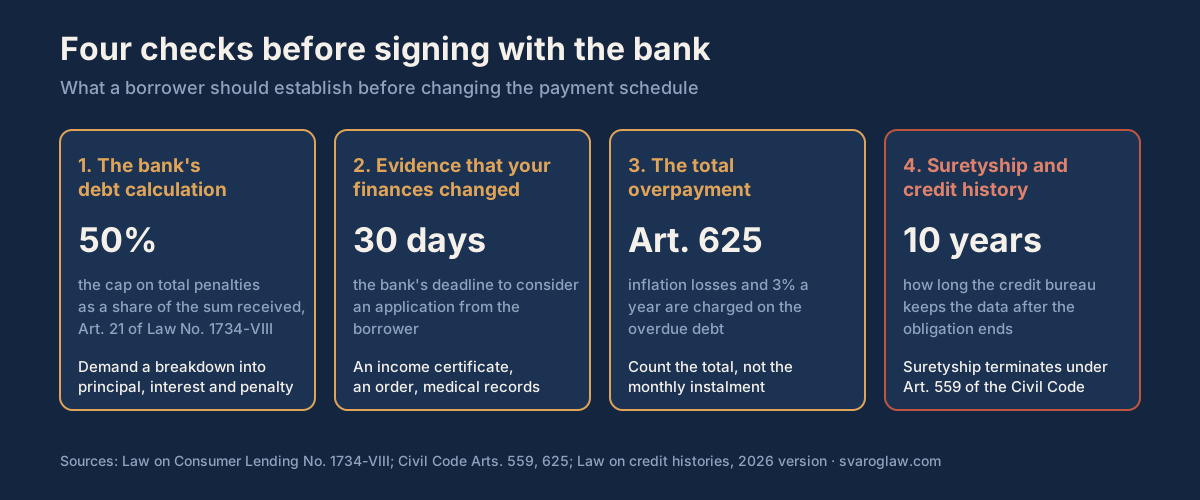
What a bank may recover beyond principal and interest is capped. Article 21 of the Law “On Consumer Lending” provides that the total penalty for a consumer’s breach may not exceed half the sum received under the contract and may not be increased by agreement. If the penalty in the bank’s calculation exceeds that ceiling, it is challenged before any talk of a schedule, and the debt falls without any restructuring at all. Checking the calculation is where our loan restructuring work begins.
Court restructuring under the Code on Bankruptcy Procedures
Where the bank has refused and the old terms are unaffordable, the procedure in the Code of Ukraine on Bankruptcy Procedures applies. Proceedings against an individual open only on the debtor’s own application. Article 115 sets out the grounds: the debtor has stopped paying more than half the monthly instalments on each obligation for two months, or has no assets to enforce against, or shows signs of impending insolvency.
The application goes to the commercial court where the debtor lives, with proof of advancing three months of the restructuring practitioner’s fee. The basic fee is five subsistence minimums for working-age people a month, that is 16,640 UAH, so the three-month advance is 49,920 UAH. That is the main reason the procedure does not suit a debt of a few tens of thousands.
Once proceedings open a moratorium applies: banks and collectors cannot pursue the debt or charge penalties, and enforcement proceedings are suspended. The practitioner prepares a restructuring plan of up to five years, which the creditors’ meeting approves and the court confirms. If the plan cannot be performed, the court declares the debtor bankrupt and moves to selling the assets, after which the remaining debts are written off, except maintenance and compensation for harm to life and health. That route is described in more detail on the page about personal bankruptcy.
| Instrument | Who decides | Timeframe | What happens to the debt |
|---|---|---|---|
| A supplemental agreement with the bank | The bank, at its discretion | up to 30 days to consider the application | stays in full; the total cost rises |
| Compulsory restructuring of a pre-24.02.2022 loan | The bank, on the borrower’s demand | repayment over up to 3 years | split into equal instalments |
| A restructuring plan under the Code | The court and the creditors’ meeting | up to 5 years | part may be forgiven by the plan |
| Bankruptcy and sale of assets | The commercial court | from 12 months | written off, except maintenance and harm to health |
What happens to penalties, collectors and the credit history
While the correspondence with the bank runs, the charges do not stop: interest accrues on the overdue sum, and under Article 625 the creditor may also claim inflation losses and three per cent per annum. Restructuring does not cancel what has already accrued unless the agreement says so expressly, so the clause writing off penalties and interest must go into the text rather than be agreed orally.
The bank may sell the claim. Since 30 July 2026 the Law “On Factoring” No. 4466-IX has regulated such operations, while conduct in recovering overdue debt is governed by the Law “On Consumer Lending”. A company demanding money from you must appear in the National Bank’s register of debt collection companies; if it does not, the calls are grounds for a complaint to the regulator. Buying your own debt at a discount is also possible and is sometimes cheaper than any restructuring — we write about that on the page on debt purchase.
A restructuring entry goes into the credit history and is read by future lenders as a sign of trouble. Information stays in the credit bureaux for ten years from the day the obligation ends, so a mortgage the year after a restructuring is not realistic.
What to do, in order
- Ask the bank for an official statement of the debt broken down into principal, interest, penalties and fees. Check whether the penalty exceeds the ceiling in Article 21 of the Law “On Consumer Lending”.
- Gather evidence that your finances have changed: an income certificate, a redundancy order, a mobilisation record, medical documents. Without them the application reads as a plea rather than a reasoned proposal.
- File a written application for restructuring with a specific schedule proposed. The bank has up to thirty days; insist on a written answer.
- Check any offer against the original contract before signing: look at the total cost, the fee for amending the terms and whether accrued penalties are written off.
- If the bank refuses and payments have stopped for more than two months, cost the insolvency procedure: 49,920 UAH of advance plus legal fees. Weigh it against the size of the debt.
- After signing, keep every receipt and statement: they are what proves the plan was performed if the bank later alleges default.
Typical mistakes
- Oral arrangements with a manager. A promise not to charge penalties “while we consider it” has no legal force: the charges keep running under the contract and are later recovered in court along with the principal.
- Signing without working out the total cost. Halving the monthly instalment while trebling the term means the total paid rises. What matters is the total, not the instalment.
- Partial payments without agreement. Paying less is not restructuring: the bank applies the money in the order set by Article 534, first to penalties and interest, and the principal barely moves.
- Ignoring the guarantee. If the terms change without the guarantor’s consent and that increases their liability, the guarantee ends under Article 559. Banks ask guarantors to sign for exactly that reason, and people sign without reading.
- Turning to insolvency over a small debt. With arrears under a hundred thousand hryvnia, the practitioner’s advance and the legal costs swallow most of the saving, so the procedure makes no sense.
When you do not need a lawyer
If there are no arrears yet, your income has simply fallen and there is one unsecured loan, the application to the bank can realistically be written alone: most banks have their own form and handle it in the app. Nor is a lawyer needed to check a collection company in the National Bank’s register or to order a credit history report. Help becomes worthwhile once the bank has sued, where the debt is secured by a mortgage or a guarantee, where there are several creditors and the total exceeds a year’s income, and where the bank’s calculation shows an inflated penalty.
Questions and answers
Must a bank agree to restructuring
As a rule no: a contract is changed by agreement under Article 651. The exception is unsecured consumer loans made before 24 February 2022, for which the final provisions of the Law “On Consumer Lending” provide compulsory restructuring on the borrower’s demand.
What does restructuring cost
Bank restructuring is usually free or carries a small fee under the tariffs. The court procedure under the Code on Bankruptcy Procedures requires three months of the practitioner’s fee in advance — 49,920 UAH in 2026 — plus legal costs. A consultation with a cost-benefit calculation at Svarog costs from 1,500 UAH and a written legal opinion from 5,000 UAH.
Does interest stop accruing while the application is considered
No. Interest and penalties accrue under the contract in force until a supplemental agreement is signed. Only the moratorium following the opening of insolvency proceedings stops them.
What if the debt has been sold to collectors
Ask for written notice of the assignment of the claim and a copy of the contract so far as it concerns your obligation. Check the company in the National Bank’s register of collection companies. The terms of the loan itself do not change, and the new creditor cannot demand more than the bank could.
Can a microloan be restructured
Yes, contractual restructuring is possible with a finance company too, and the cap on total penalties in the Law “On Consumer Lending” applies to such contracts as well. In practice microfinance firms prefer to offer an extension for a fee, so recalculate the actual cost of the loan first.
Will the flat be taken in a personal bankruptcy
A home that is mortgaged forms part of the estate, and the restructuring plan must account for the secured creditor’s claim. A sole home free of any mortgage is protected by restrictions, but the court decides each case on its facts, so the forecast must be made before the application is filed.
Does restructuring damage a credit history
Yes; the change of terms is reported to the credit bureaux and stays there for ten years from the day the obligation ends. That said, lenders read a restructuring entry more kindly than arrears of over ninety days or a court recovery.
Can penalties be written off by agreement
Yes, a bank may forgive accrued penalties, and in practice does so where the borrower repays part of the principal in one payment. The write-off must be stated expressly in the agreement with the amount given, or it does not work.
How long does the insolvency procedure take
Several months pass between filing and the restructuring plan being approved, and performing the plan can take up to five years. Where the court moves to declaring the debtor bankrupt and selling assets, the whole process rarely takes less than a year.
Sources
- Law of Ukraine “On Consumer Lending”, Arts. 17, 21 — zakon.rada.gov.ua/laws/show/1734-19
- Code of Ukraine on Bankruptcy Procedures, Arts. 115, 116 and the section on restoring an individual’s solvency — zakon.rada.gov.ua/laws/show/2597-19
- Civil Code of Ukraine, Arts. 534, 559, 604, 625, 651 — zakon.rada.gov.ua/laws/show/435-15
- Law of Ukraine “On Factoring” No. 4466-IX — zakon.rada.gov.ua/laws/show/4466-20
- National Bank of Ukraine register of debt collection companies — bank.gov.ua
Loan debt restructuring with Svarog
We begin by checking the bank’s calculation: often the penalty turns out to exceed the statutory ceiling, and the debt falls before any negotiation. Then we prepare the application with a reasoned schedule, handle the correspondence with the bank and, where agreement proves impossible, work out whether insolvency is worthwhile in your situation and run it in the commercial court. Prices for individual services are on the page of legal service prices, and the practice as a whole in the section on debt restructuring.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00