
Олександр Сич
2 April 2026
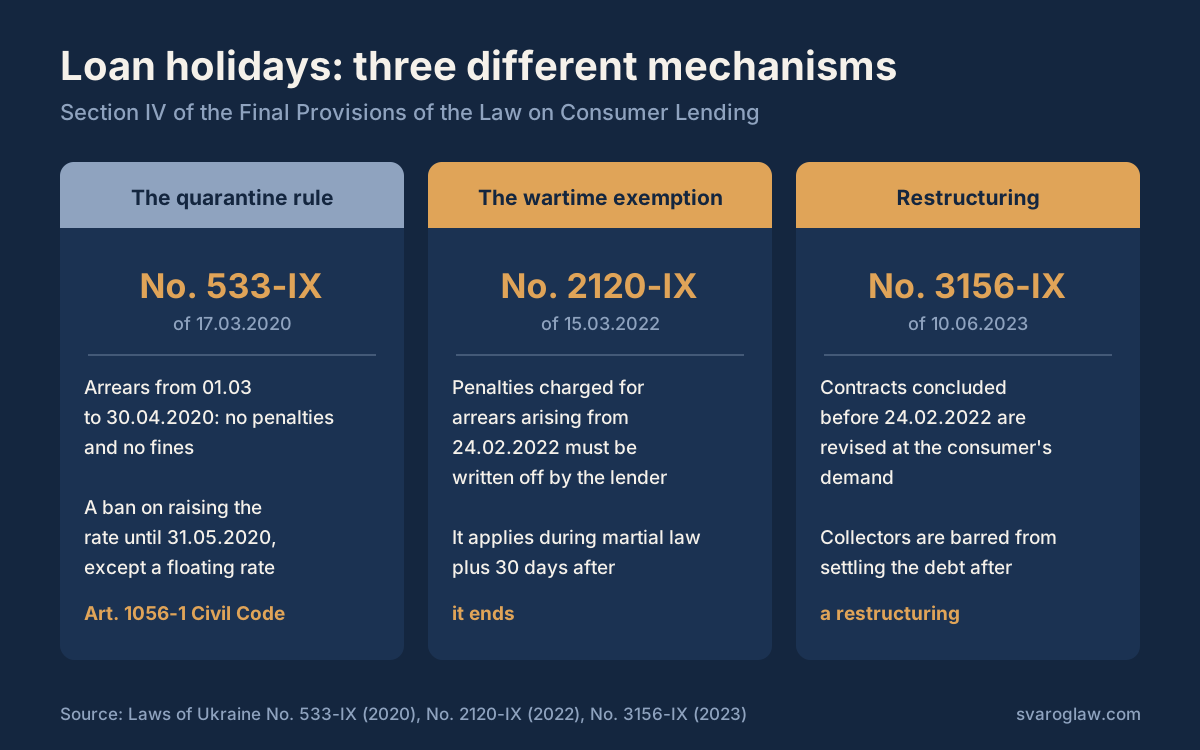
There is no separate “credit holidays” law in Ukraine. In its place three different mechanisms operate: the quarantine rule of Law No. 533-IX for arrears between 1 March and 30 April 2020, the wartime release from penalties under Law No. 2120-IX from 24 February 2022, and mandatory restructuring under Law No. 3156-IX. None of them writes off the principal.
On 17 March 2020 parliament passed Law No. 533-IX, adding to Chapter IV “Final and transitional provisions” of the Law “On Consumer Lending”: a consumer who fell into arrears between 1 March and 30 April 2020 was released from paying penalties and other charges for those arrears, and raising the interest rate between 1 March and 31 May 2020 was prohibited, save for floating rates under part four of Article 1056-1 of the Civil Code. It was this provision that the press called “credit holidays”, though holidays it was not.
Six years on, borrowers are living with the consequences: banks and microfinance companies charge penalty interest for periods in which they had no right to charge it, debt collectors demand sums calculated without the wartime rules, and courts write such charges off as a defence to the claim. Below we set out which borrower protections are in force in 2026, who they cover and what to do about penalties already charged.
Why “credit holidays” do not exist as a separate institution
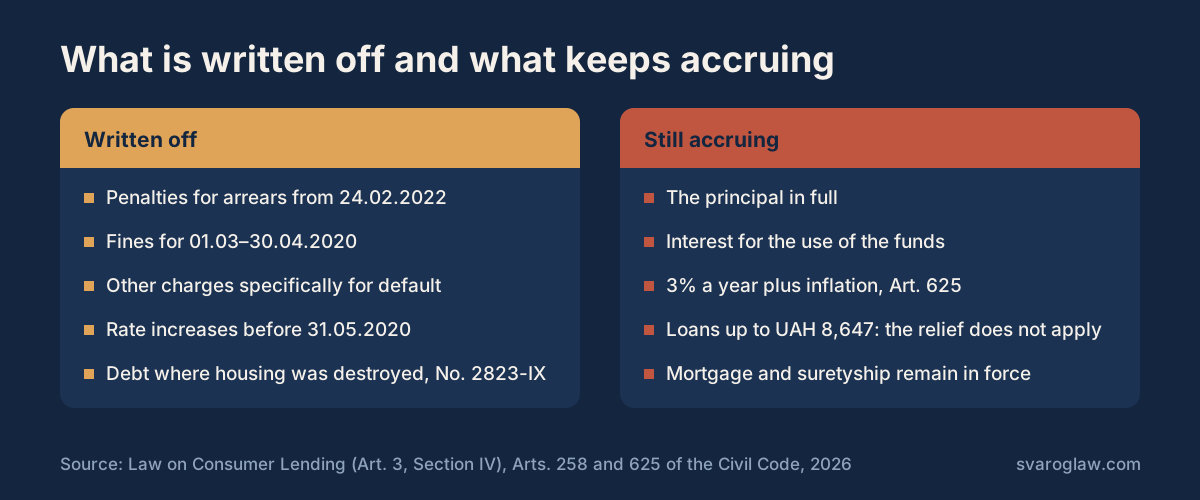
In everyday speech “holidays” suggests payments are simply pushed back with no consequences. No Ukrainian provision says that. The legislature released the borrower only from liability for the arrears: from penalties, fines, default interest and other charges imposed by the contract precisely for non-performance. The principal and the interest for using the money kept accruing, because that is the price of the money, not a sanction.
The second boundary concerns which contracts are covered. Part two of Article 3 of the Law “On Consumer Lending” takes several kinds of agreement outside that law: credit agreements for up to one month and account credit repayable within a month, interest-free loans, unauthorised overdrafts, pawnshop loans against security, and agreements where the total credit does not exceed one minimum wage on the day of signing. In 2026 the minimum wage is 8,647 UAH, so a microloan of 5,000 UAH falls outside the law’s protection. That is the central defect of the 2020 quarantine rule: it was extended to contracts the law itself does not govern, and the resulting conflict of provisions was then left to the courts.
Wartime borrower protections from 24 February 2022
Law No. 2120-IX of 15 March 2022 added to the same final provisions a rule for martial law: where a consumer falls into arrears under a consumer credit agreement during martial law and for thirty days after it ends or is lifted, the consumer is released from liability to the lender, and penalties and other charges imposed for such arrears from 24 February 2022 are to be written off by the lender.
The legislature then refined this several times. Law No. 2459-IX of 27 July 2022 restricted contact by lenders and debt collection companies with protected categories: service members, prisoners of war, the missing and the families of those killed. Law No. 2823-IX of 1 December 2022 gave the right to suspend payments on loans secured by housing in temporarily occupied territories or damaged by the armed aggression, and provided for the debt to be cancelled where such housing is destroyed. The practical side of these rules is handled by a credit disputes lawyer, because each has its own class of persons and its own list of documents.
| Mechanism | Law and date | Who it covers | What it gives |
|---|---|---|---|
| Quarantine rule | No. 533-IX of 17.03.2020 | arrears 01.03–30.04.2020 | release from penalties, no rate increases until 31.05.2020 |
| Wartime release from liability | No. 2120-IX of 15.03.2022 | consumer credit, arrears from 24.02.2022 | write-off of penalties and other charges for the arrears |
| Protection of certain categories | No. 2459-IX of 27.07.2022 | service members, prisoners of war, families of the fallen | ban on debt collection activity at the lender’s initiative |
| Housing in occupied territory and destroyed housing | No. 2823-IX of 01.12.2022 | mortgages over damaged or lost housing | suspension of payments, cancellation of the debt if the housing is destroyed |
| Mandatory restructuring | No. 3156-IX of 10.06.2023 | agreements signed before 24.02.2022 | revision of terms at the consumer’s request, limits on interest |
Mandatory restructuring under Law No. 3156-IX
Law No. 3156-IX of 10 June 2023 addressed disproportionate charges for people whose housing ended up in a combat zone or on occupied territory. Monetary obligations under consumer credit agreements signed before 24 February 2022 are subject to mandatory restructuring at the request of the consumer or their representative during martial law and for thirty days after it ends. The restructuring is set out in an agreement recording the new terms, and debt collectors are barred from pursuing arrears on restructured obligations.
The application goes to the lender in writing, with documents proving the ground: a displaced person’s certificate, an inspection report on damaged housing, an extract from the register of damaged and destroyed property, or service documents. The bank has no right to refuse by reference to its own internal rules, which is why loan restructuring starts with a written application sent with a list of contents — a phone call with a manager is not evidence.
What to do if the bank charged penalties anyway
- Ask the lender for a detailed statement of the debt broken down by period: principal, interest, penalties, commissions. Without that document the dispute becomes an exchange of assumptions.
- Compare the periods in which penalties were charged against 01.03–30.04.2020 and against the period after 24.02.2022: sums charged in those windows are to be written off.
- Send the lender a written demand for recalculation by registered post with a list of contents; the time allowed to answer a financial services consumer is set by law and runs from the date of receipt.
- If there is no answer, complain to the National Bank of Ukraine as the regulator of the consumer lending market, enclosing the calculation and a copy of the demand.
- Plead limitation if the lender goes to court: claims for penalties are subject to the shortened one-year period under clause 1 of part two of Article 258 of the Civil Code, and limitation, suspended from 2 April 2020, resumed running on 4 September 2025 under Law No. 4434-IX.
- Consider whether personal insolvency proceedings would serve better where the total debt exceeds what you can realistically pay: they close the obligations rather than postponing them.
What the protections do not cover
Interest for the use of the credit accrues throughout, and none of these provisions cancels it. The consequences of Article 625 of the Civil Code likewise remain: a debtor in default on a monetary obligation pays, at the creditor’s demand, the debt adjusted for the inflation index over the whole period of default plus three per cent per annum, unless the contract sets a different rate. Case law distinguishes this from a penalty, so writing off default interest does not automatically remove an Article 625 claim.
The security does not disappear either. Mortgages and guarantees continue to operate, enforcement under previously issued documents is not terminated by the protection itself, and the encumbrance stays on the register until the debt is repaid in full. Once matters reach compulsory enforcement, the question moves into the area of debt recovery and the lawfulness of the enforcement officer’s actions, where credit holidays decide nothing.
Typical mistakes borrowers make
- Stopping payment altogether in the belief that “holidays” apply. The release covers only penalties, while arrears of principal and interest build a debt and damage the credit record.
- Agreeing things orally. A manager’s promise to “charge nothing” is not evidence; only a written answer from the lender or a signed restructuring agreement counts.
- Counting on protection for a microloan of a few thousand hryvnias. Agreements up to one minimum wage — up to 8,647 UAH in 2026 — fall outside the Law “On Consumer Lending”.
- Not pleading limitation. The court does not apply it of its own motion, and after the first-instance judgment such a plea no longer has effect.
- Signing a restructuring agreement without reading the final figure. New terms often capitalise the accrued penalty into the principal, and what was written off returns to the payment schedule.
When you do not need a lawyer
If you are paying on schedule, there are no arrears, and the question is only whether the charges are right, you can manage alone: ask the bank for the detailed statement, compare the penalty periods with the dates above and send a written demand for recalculation. Your credit record can be checked yourself at a credit bureau, and a complaint to the National Bank is filed through its official website without a representative. A lawyer becomes necessary when the lender has filed a claim or applied for a court order, when the debt has gone to collectors, when a home mortgage is involved, or when the charges exceed the principal: in those situations the cost of a mistake outweighs the cost of representation.
Questions and answers
Are credit holidays in force in Ukraine in 2026
There are no separate “holidays”. What operates is the release from liability for arrears on consumer credit during martial law and for thirty days after it ends, plus the right to demand mandatory restructuring under Law No. 3156-IX.
Can you stop paying a loan during martial law
No. The release covers penalties, fines and default interest, while the principal and the interest for using the money keep accruing and remain payable.
Must penalties charged since 24 February 2022 be written off
Under Law No. 2120-IX, penalties and other charges imposed for arrears on consumer credit from 24 February 2022 are to be written off by the lender. If the lender has not done so, demand a recalculation in writing.
Do the protections cover microfinance loans
Not always. Agreements for a sum not exceeding one minimum wage on the day of signing, and credit for up to one month, are taken outside the Law “On Consumer Lending” by part two of its Article 3.
What does mandatory restructuring give
A revision of the terms of an agreement signed before 24 February 2022 at the consumer’s request: a new schedule and limits on charges. The terms are recorded in a separate agreement, and collectors are barred from pursuing the restructured obligation.
What documents are needed for restructuring
An application to the lender plus documents proving the ground: a displaced person’s certificate, an inspection report on damaged housing, an extract from the register of damaged and destroyed property, or service documents.
Do the three per cent per annum and inflation adjustment still accrue
Yes. Article 625 of the Civil Code requires a debtor in default on a monetary obligation to pay the debt adjusted for the inflation index plus three per cent per annum, and these sums are not penalties.
What is the limitation period for recovering penalties
One year under clause 1 of part two of Article 258 of the Civil Code. Limitation, suspended from 2 April 2020, resumed running on 4 September 2025 under Law No. 4434-IX.
Can debt collectors call a service member
Law No. 2459-IX of 27 July 2022 restricts contact initiated by lenders and debt collection companies with service members, prisoners of war, the missing and the families of those killed.
Where do you complain about a bank or a microfinance company
To the National Bank of Ukraine as the regulator of the financial services market, and, as regards breaches in pursuing arrears, also to law enforcement where collectors’ conduct goes beyond the law.
Sources
- Law of Ukraine “On Consumer Lending”, Article 3 and Chapter IV “Final and transitional provisions”
- Law of Ukraine No. 533-IX of 17.03.2020 (quarantine amendments)
- Law of Ukraine No. 2120-IX of 15.03.2022
- Law of Ukraine No. 3156-IX of 10.06.2023 on interest on consumer credit during martial law
- Civil Code of Ukraine, Articles 258, 625, 1056-1
- National Bank of Ukraine: complaints from financial services consumers
- Free Legal Aid system: materials on credit holidays
Credit disputes with Svarog
We check the debt calculation period by period, prepare the demand to write off penalties, handle mandatory restructuring and defend claims brought by banks, microfinance companies and collectors. A consultation costs from 1,500 UAH and a written legal opinion on your agreement from 5,000 UAH; pre-action settlement starts at 5,000 UAH and full handling of a civil case at 25,000 UAH; the other items are on the legal services price list page.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00