Олександр Сич
9 April 2026
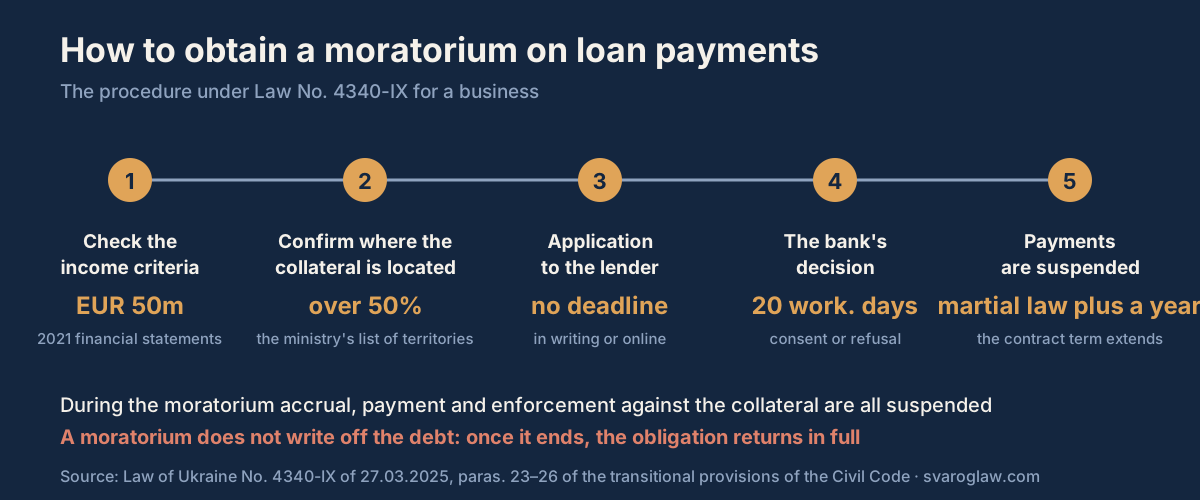
Payment holidays for business in 2026 rest on Law No. 4340-IX: an entrepreneur whose 2021 annual income was under EUR 50 million, and more than half of whose security lies in an area of active hostilities or in occupied territory, files an application with the lender, which decides within 20 working days. The moratorium runs for the whole of martial law and a year after it ends.
Law of Ukraine No. 4340-IX, passed on 27 March 2025 and signed on 8 August the same year, added to the “Final and transitional provisions” of the Civil Code a separate mechanism for suspending payments under loans and finance leases. It is the first instrument since 2022 that works not as a bank’s goodwill but as a borrower’s statutory right where specific conditions are met.
Everything else remains contractual: a bank may change the schedule, extend the term, cut the monthly instalment or reduce it to interest only, but it is obliged to do so only where it agrees. Below: who falls within the statutory moratorium, how to negotiate with a bank outside it, and how an arrears problem left unattended ends.
Holidays, moratorium and restructuring: three different things
Payment holidays in the everyday sense mean a pause after which the schedule resumes. The bank usually offers interest-only payments and moves the principal to the end of the term, so the total cost rises. Restructuring changes the contract for good: it extends the term, changes the rate, rolls arrears into the principal or writes off part of the penalties.
The moratorium under Law No. 4340-IX works differently. It suspends the accrual and payment of monetary obligations — principal, interest, commissions and other charges — and the term of the contract itself is automatically extended by the period of suspension. Enforcement measures and enforcement against the security stop for that time. None of the three writes off the debt: once the relief period ends, the obligation returns in full.
Who is entitled to the moratorium under Law No. 4340-IX
The mechanism is designed for businesses that have physically lost access to their own assets. The right to suspend payments arises for a borrower that is a business entity and meets four conditions at once: aggregate 2021 income together with related parties not exceeding the equivalent of EUR 50 million; income for the previous reporting year not exceeding 75 % of the 2021 figure; a loan agreement made before the Law took effect; and more than 50 % of the value of the security located in areas of active hostilities or in temporarily occupied territories.
The application goes to the lender in writing or electronically with the borrower’s signature; the Law sets no filing deadline. The lender decides to apply the moratorium or to refuse within 20 working days of receiving the documents. The suspension lasts for the duration of martial law and one year from the day it ends or is lifted. Whether property falls within the relevant territory is confirmed against the current list of areas of active hostilities and temporarily occupied territories maintained by the Ministry for Communities and Territories Development.
If the company falls outside the moratorium
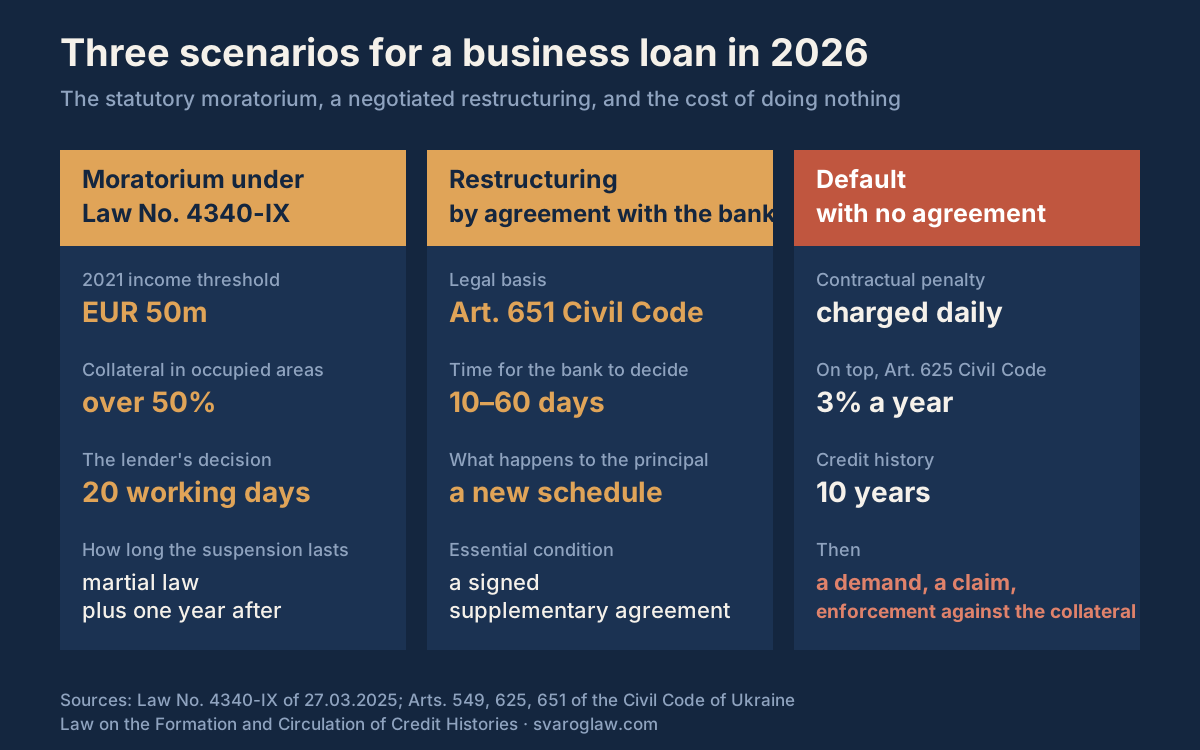
Most entrepreneurs whose assets sit in the rear regions are left in the field of negotiated arrangements. Contract terms are changed under Article 651 of the Civil Code by agreement, and the bank assesses each approach on its own criteria: recent financial statements, turnover trends, the sector, the state of the security and the payment record before the approach. Those who come before the first missed payment get better terms than those who appear after three.
| Option | Legal basis | Time to a decision | What happens to the debt |
|---|---|---|---|
| Business moratorium | Law No. 4340-IX, paras. 23–26 of the Civil Code transitional provisions | 20 working days | Payments and accruals suspended, the term extended |
| Payment holidays by agreement with the bank | Art. 651 of the Civil Code, the bank’s own rules | Per the lender’s internal rules | Interest only, principal deferred |
| Restructuring | Art. 651 of the Civil Code, a supplemental agreement | From 10 days to two months | A new schedule, sometimes a different rate and term |
| Rehabilitation before proceedings open | Art. 5 of the Code on Bankruptcy Procedures | Per the plan agreed with creditors | A plan for restoring solvency |
| Doing nothing | Arts. 549, 625 of the Civil Code | — | Contractual penalties, 3 % per annum and inflation losses |
When talks with the bank reach a dead end, what remains is pre-action settlement with a structured proposal and a solvency calculation. That work is described on the page about loan restructuring, and dealing with debt already in arrears in the section on debt restructuring.
What it costs, and the point at which insolvency is better
A consultation reviewing the loan agreement and assessing the chances of a moratorium costs from 1,500 UAH, a written legal opinion with the criteria worked through from 5,000 UAH, and preparing the application and handling the negotiations with the bank as part of pre-action settlement from 5,000 UAH. If the bank has already sued, court representation starts at 10,000 UAH and full handling of a commercial case at 30,000 UAH. The rate for each item is on the page of legal service prices.
Where the debt exceeds the value of everything the company owns and operations are not recovering, negotiating a schedule stops making sense. It is then more rational to cost out a company insolvency, in which the debts are fixed as at the date proceedings open and penalties stop accruing.
Step by step: arranging a pause in payments
- Check the criteria in Law No. 4340-IX. Pull the 2021 financial statements and the latest reporting period, take the euro rate as at the calculation date and work out the share of the security in the relevant territories.
- Prepare the supporting documents. An extract from the State Register of Real Property Rights for the pledged asset, a certificate of its location, the accounts, and the income calculation including related parties.
- File the application with the lender. In writing or electronically with the borrower’s signature; record the date of delivery, from which the 20 working days run.
- Wait for the bank’s answer. The decision to apply the moratorium, or a reasoned refusal, is given within 20 working days.
- If the moratorium does not apply, move to negotiations. The proposal to the bank should contain a 6–12 month cash-flow forecast and an affordable instalment, not a request to be understanding.
- Record the agreement in a supplemental agreement. A manager’s verbal promise does not change the schedule: without a signed document, arrears keep accruing.
Typical mistakes entrepreneurs make
- A pause with nothing in writing. Until the supplemental agreement is signed, the bank keeps accounting on the old schedule, charges penalties and reports to the credit bureaux.
- Approaching after three missed payments. The credit committee looks at the payment record up to the approach, and arrears sharply narrow the terms on offer.
- Calculating income without related parties. The Law requires aggregate income including related parties, and understating it gives the bank grounds to refuse the moratorium.
- Ignoring limitation. Since 4 September 2025 the three-year period under Article 257 runs without the quarantine suspension, so old bank claims need their dates checked separately.
- Selling pledged assets “to pay it off”. Disposing of pledged property without the pledgee’s consent entitles it to demand early repayment of the whole loan.
When you do not need a lawyer
If the company has one loan with a few hundred thousand hryvnia outstanding, no arrears, and the bank is offering a standard deferral programme on its own form, there is no need for outside help. The finance director files the accounts, signs the supplemental agreement and keeps the new schedule. Nor is help needed where an entrepreneur decides to repay the balance early and asks the bank to recalculate the interest.
A lawyer is needed where there are several loans at different banks, where the security is property in front-line areas, where the bank has already demanded early repayment or has transferred the debt to a finance company. Assessing the debt portfolio and the negotiating strategy in such cases falls within our work on loans and microcredit.
Questions and answers
Who is entitled to business payment holidays in 2026
The statutory moratorium under Law No. 4340-IX is open to business entities with 2021 income up to EUR 50 million whose income for the previous reporting year does not exceed 75 % of the 2021 level, whose loan agreement predates the Law, and more than half of whose security lies in an area of active hostilities or in occupied territory.
How long does the bank take to decide on a moratorium
Twenty working days from receiving the application and the supporting documents. The lender then either applies the moratorium or gives a reasoned refusal, which can be challenged in court where the statutory conditions are met.
Does interest accrue during the moratorium
No. The accrual and payment of monetary obligations — principal, interest and commissions — are suspended, and the term of the contract is extended by the period of suspension. That is what distinguishes the moratorium from ordinary payment holidays, under which interest usually keeps running.
Will payment holidays spoil the credit history
A deferral recorded in an agreement is not an arrears event and does not damage the history. Records of missed payments, by contrast, stay in the credit bureaux for ten years after the obligation ends and affect the terms of new borrowing.
What to do if the bank refuses to restructure
Get the refusal in writing, check the contract for unfair terms, work out limitation for each instalment and prepare a counter-proposal with financial reasoning. If the bank has sued, the defence is built around the calculation of the debt, the size of the penalties and the proportionality of the claim.
Can penalties be stopped during martial law
For consumer loans to individuals there is a ban on charging penalties for the duration of martial law and thirty days afterwards. That rule does not extend to loans to business entities, so for a business the moratorium under Law No. 4340-IX or a negotiated arrangement is what works.
Does the bank take the security as soon as a payment is missed
No; first a demand to remedy the breach is sent, and only after the period it sets expires does the lender go to court or to a notary for an enforcement endorsement. During a moratorium under Law No. 4340-IX enforcement against the security stops.
What does legal help with bank negotiations cost
A consultation with a review of the contract from 1,500 UAH, a written opinion from 5,000 UAH, and pre-action settlement including the proposal and the negotiations from 5,000 UAH. The court stage starts at 10,000 UAH, and full handling of a commercial case at 30,000 UAH.
Can a sole trader get holidays on a microcredit
Finance companies are not obliged to grant deferrals and rarely do so voluntarily. The real tools for a sole trader are negotiating a schedule recorded in a supplemental agreement, challenging the penalties charged, or the personal debt restructuring procedure under the Code on Bankruptcy Procedures.
Which is better: restructuring or insolvency
Restructuring makes sense while the business generates income and the debt can be serviced on a longer schedule. Once the obligations exceed the value of the assets, insolvency fixes the debt as at the date proceedings open and stops penalties accruing, which is often cheaper than years of fruitless negotiation.
Sources
- Law of Ukraine No. 4340-IX of 27.03.2025 on lending and finance leasing during martial law — zakon.rada.gov.ua/laws/show/4340-20
- Civil Code of Ukraine, Arts. 257, 549, 625, 651 and the transitional provisions — zakon.rada.gov.ua/laws/show/435-15
- Code of Ukraine on Bankruptcy Procedures — zakon.rada.gov.ua/laws/show/2597-19
- National Bank of Ukraine, section on borrowers’ rights — bank.gov.ua
- Ministry for Communities and Territories Development of Ukraine, list of areas of active hostilities and temporarily occupied territories — mininfra.gov.ua
- Law of Ukraine “On the Organisation of the Formation and Circulation of Credit Histories” — zakon.rada.gov.ua/laws/show/2704-15
Business payment holidays with Svarog
We check whether the company falls within the moratorium under Law No. 4340-IX, prepare the application with its supporting documents, negotiate a new schedule with the bank and defend the business in court where the lender is already demanding early repayment. If the bank has sent a demand, come to us before the period it sets expires: after that the range of workable solutions narrows noticeably. We handle the pre-action stage as part of pre-action settlement of commercial disputes.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00