Олександр Сич
10 April 2026
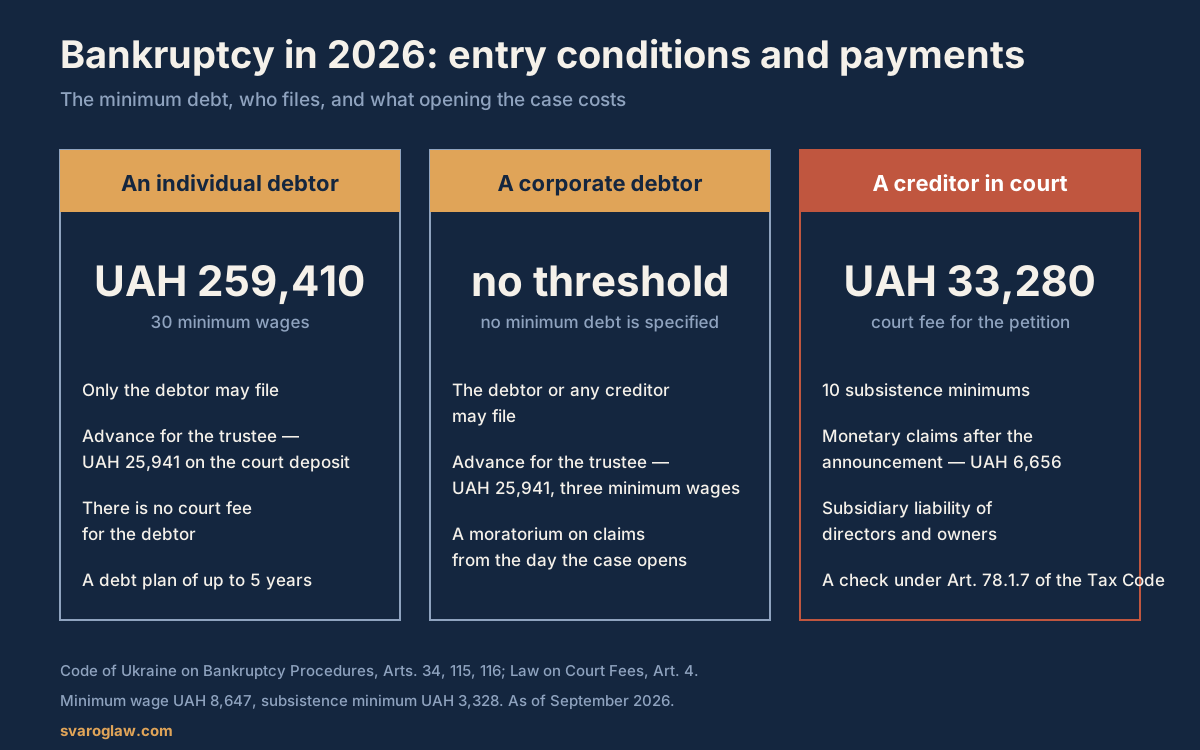
An individual can open insolvency proceedings only on their own application: with overdue obligations of 30 minimum wages or more, that is 259,410 UAH in 2026, or after enforcement proceedings have produced nothing. There is one compulsory payment — an advance of 25,941 UAH for the insolvency practitioner’s fee, paid into the court’s deposit account. A creditor can start a company’s insolvency with no debt threshold at all.
The Code of Ukraine on Bankruptcy Procedures has been in force since 21 October 2019 and abolished two rules that older articles still mention: the threshold of 300 minimum wages for a creditor’s application, and the impossibility of a private individual going bankrupt. Since then a company can be put into a procedure over any undisputed debt, and individuals have their own part of the Code, with restructuring and the writing off of the balance.
The other half of the truth is that there is no such thing as a free bankruptcy. The applicant advances three months of the insolvency practitioner’s fee, a creditor adds a court fee of 33,280 UAH, and an individual declared bankrupt must tell banks of that status for five years. Below: the conditions for opening proceedings, the real cost, the debts that are never written off, and the consequences worth knowing about before filing.
When insolvency proceedings can be opened
For individuals and sole traders, Article 115 applies: proceedings are opened only on the debtor’s own application, and no creditor can force a private individual into bankruptcy. One of four conditions suffices: overdue obligations of 30 minimum wages or more; ceasing to pay more than 50 % of the monthly instalments on loans for two months; a bailiff’s finding that there are no assets to enforce against; or other circumstances showing an inability to pay in the near future. Penalties, interest and other sanctions do not count towards the monetary claims, so the threshold is measured against the principal.
With companies the logic is the opposite. Both the debtor and a creditor may apply, and the Code sets no minimum for undisputed claims — the 300 minimum wage rule belonged to the repealed Law “On Restoring the Solvency of a Debtor”, and citing it in 2026 is a mistake. A creditor’s application must be accompanied by proof of the court fee and of the advance of the insolvency practitioner’s fee, three minimum wages for three months in office.
| Question | Individual | Company |
|---|---|---|
| Who may apply | Only the debtor | The debtor or any creditor |
| Minimum debt | From 30 minimum wages (259,410 UAH), or another ground in Art. 115 | No threshold |
| Court fee on the application | No rate is set for the debtor | 10 subsistence minimums — 33,280 UAH from a creditor |
| Advance to the insolvency practitioner | 25,941 UAH into the court’s deposit account | 25,941 UAH into the court’s deposit account |
| Main procedures | Debt restructuring or debt repayment | Asset administration, rehabilitation, liquidation |
| How it ends | Writing off the remaining debts, with exceptions | Liquidation or restored solvency |
What the procedure costs
The main expense is advancing three months of the insolvency practitioner’s fee: three minimum wages, that is 25,941 UAH at the 2026 rate of 8,647 UAH. The money goes not to the practitioner but into the commercial court’s deposit account, and without proof of that payment the court stays the application. A creditor adds the 33,280 UAH court fee for the application to open proceedings, and every creditor lodging monetary claims after the official announcement pays 2 subsistence minimums, that is 6,656 UAH.
After that the budget depends on the assets. A property valuation or a car valuation, register extracts, notarised copies and publications in the Unified Register are all paid for by the debtor or by the creditor who started the case. Legal fees are separate: handling an individual’s bankruptcy and handling a company’s insolvency differ in paperwork and in the number of hearings; indicative figures are on the page of legal service prices.
Which debts are written off and which remain
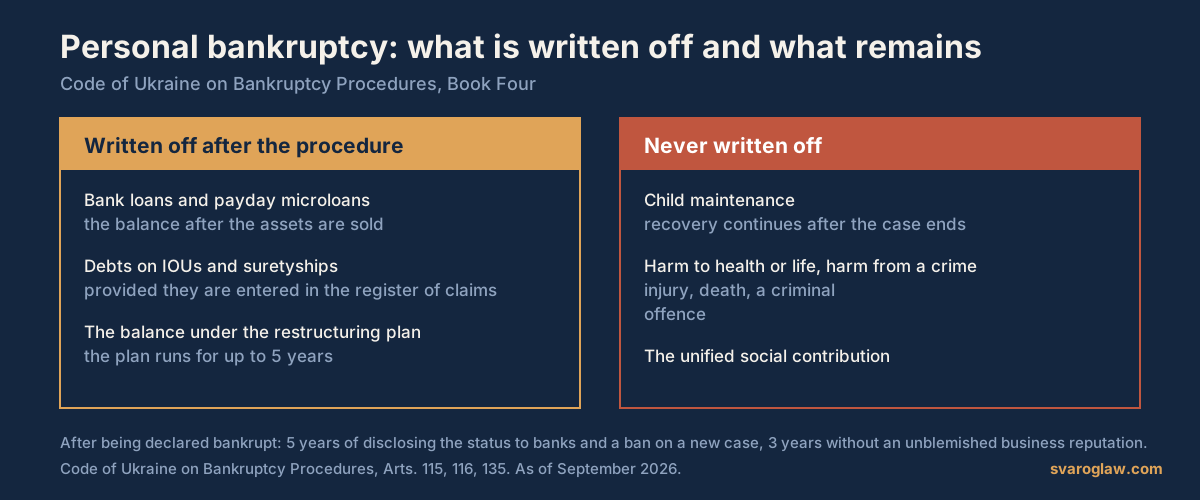
The point of an individual’s bankruptcy is that once the assets are sold and the creditors paid, the unpaid balance is written off. The Code makes exceptions, and they matter: it does not release you from maintenance obligations, from compensating harm caused by injury, other damage to health or death, from compensating harm caused by a criminal offence, or from the unified social security contribution.
Debts the debtor concealed from the court are not written off either. A creditor left off the list in the application never enters the register of claims, and once the case closes they will pursue the debt in the ordinary way. So the list of creditors is compiled from statements from every bank and from requests to the credit bureaux, not from memory. Where loans are joined by high-interest microcredit, it is worth costing the alternative first: debt restructuring is sometimes cheaper than a full procedure.
Opening proceedings, step by step
- Gather the documents on the debts and the assets: loan agreements, arrears calculations, extracts from the State Register of Real Property Rights, vehicle records, a declaration of assets, a copy of the employment record book.
- Draw up the list of creditors with the sums and the basis of each debt. For an individual it is the foundation of the register of claims; for a company it is the basis for checking that claims are undisputed.
- Prepare a draft debt restructuring plan if the debtor is an individual: the Code requires it to be filed with the application, and the plan may not run longer than five years.
- Transfer the advance for the insolvency practitioner — 25,941 UAH into the commercial court’s deposit account — and, if you are a creditor, pay the 33,280 UAH court fee.
- File the application with the commercial court where the debtor lives or the company is located. The court checks the documents, opens the proceedings, appoints a practitioner and imposes a moratorium on satisfying creditors’ claims.
- Go through the procedure: for an individual, debt restructuring, and if no plan is possible, debt repayment with the sale of assets; for a company, asset administration, rehabilitation or liquidation.
Consequences people learn about too late
Opening proceedings against a business is a ground for an unscheduled documentary audit by the tax authority under subparagraph 78.1.7 of the Tax Code. That is not a punishment but the tax service’s standard reaction to liquidation procedures beginning; still, anything it finds ends in assessments and penalties that become claims in the same case.
Directors and founders are not left out either. The Code allows subsidiary liability for the debtor’s obligations to be imposed on them where the insolvency was their fault, in particular where assets were moved out on the eve of the application. For an individual the consequences are milder but long: for five years after being declared bankrupt they must disclose that status when taking a loan or credit and cannot open insolvency proceedings again, and for three years they are not treated as a person of impeccable business reputation.
Typical mistakes
- Selling or gifting assets on the eve of the application. Transactions within the period the Code sets before proceedings open are declared invalid, the assets return to the estate, and the conduct is treated as abuse.
- An incomplete list of creditors. A debt not declared in the case is not written off, and once the case closes the creditor returns with a writ of execution.
- An application without the advance. The court stays it, while the interest and penalties keep running.
- Expecting a “quick” write-off. Restructuring is designed to run for up to five years, and only when it fails does the court move to the repayment procedure.
- Citing repealed provisions. The 300 minimum wage threshold for a creditor’s application went with the Law “On Restoring the Solvency of a Debtor”, and a defence built on it will not work.
When you do not need a lawyer
If there are a few debts, all of them bank loans, no assets, and a bailiff has already recorded that there is nothing to enforce against, the application can realistically be prepared alone from the list of documents in Article 116. After that the insolvency practitioner effectively runs the procedure, and the debtor’s role comes down to supplying documents and answering requests.
It is a different matter where there is mortgaged property, spouses’ joint assets, guarantee debts, corporate rights, or creditors alleging that assets were moved out. There every procedural step bears on whether the home survives and whether the case turns into a question of subsidiary liability. Where a microcredit firm is enforcing a debt whose charges exceed the principal, it is worth assessing the prospects of a dispute with a loans and microcredit lawyer first: sometimes challenging the calculation is enough, without any bankruptcy.
Questions and answers
Can a creditor declare an individual bankrupt
No. Article 115 of the Code of Ukraine on Bankruptcy Procedures allows proceedings against an individual or a sole trader to be opened only on the debtor’s own application, whatever the size of the debt.
What minimum debt does an individual need for bankruptcy
One ground is overdue obligations of 30 minimum wages or more, that is 259,410 UAH in 2026. But another ground will do: ceasing to pay more than 50 % of the monthly instalments for two months, or a bailiff’s finding that there are no assets.
What does filing a bankruptcy application cost
The compulsory payment is the 25,941 UAH advance for the insolvency practitioner, paid into the court’s deposit account. A creditor additionally pays the 33,280 UAH court fee on the application to open proceedings.
Is maintenance written off in bankruptcy
No. Maintenance arrears, compensation for harm caused by injury or death, compensation for harm from a criminal offence and the unified social security contribution are not written off even when the procedure ends.
Is the 300 minimum wage threshold needed for a company’s insolvency
No, that threshold belonged to the repealed Law “On Restoring the Solvency of a Debtor”. The Code in force sets no minimum for a creditor’s undisputed claims.
How long does the procedure take
The timeframes depend on the procedure and on the assets. For an individual the restructuring plan is designed to run for up to five years, and company cases involving rehabilitation or liquidation usually last from several months to several years.
Will the only home be taken
The home forms part of the estate, and the Code has special rules for a flat bought with a mortgage. The prospects depend on whether there is a mortgage, who is registered as living there and what the restructuring plan says, so this is assessed before the application is filed.
What happens to a guarantor
The debtor’s bankruptcy does not release the guarantor. The creditor may enforce the debt against the guarantor in the ordinary way, and the guarantor, having paid, lodges their own claim in the bankruptcy case.
Will the tax authority audit the company after the case opens
Yes, the opening of insolvency proceedings is a ground for an unscheduled documentary audit under subparagraph 78.1.7 of the Tax Code. Any additional assessments become creditor’s claims in the same case.
What restrictions follow an individual being declared bankrupt
For five years they must disclose that status when entering into credit agreements and cannot open insolvency proceedings again, and for three years they are not treated as a person of impeccable business reputation.
Sources
- Code of Ukraine on Bankruptcy Procedures, Arts. 34, 115, 116, 135 — zakon.rada.gov.ua/laws/show/2597-19
- Law of Ukraine “On Court Fees”, Art. 4 — zakon.rada.gov.ua/laws/show/3674-17
- Tax Code of Ukraine, subparagraph 78.1.7 — zakon.rada.gov.ua/laws/show/2755-17
- Unified State Register of Court Decisions — reyestr.court.gov.ua
- Ministry of Justice of Ukraine: insolvency practitioners and registers — minjust.gov.ua
Bankruptcy procedures with Svarog
We work out whether bankruptcy is worthwhile in your situation, prepare the application with the restructuring plan, attend the hearings and defend directors against unfounded claims of subsidiary liability. If the procedure is not worth it, we say so at the consultation and offer the alternative — from restructuring to a dispute about how the debt was calculated.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00