Олександр Сич
10 April 2026
From 30 July 2026 factoring in Ukraine is governed by its own statute, Law No. 4466-IX. The contract must be in writing and state the type of factoring, the price and the deadlines; assignments are entered in a dedicated register, and the factor must notify the debtor within three working days of registration.
Parliament passed the Law of Ukraine “On Factoring” No. 4466-IX on 3 June 2025; it took effect on 30 July 2025 and came into operation a year later, on 30 July 2026. Until then factoring was governed by the general provisions of Chapter 73 of the Civil Code, and it was their brevity that generated arguments about how a factoring contract differs from an ordinary assignment of a claim.
Factoring gives a supplier money today for goods the buyer will pay for in thirty or sixty days. A finance company or a bank buys the monetary claim at a discount and then collects payment from the debtor. For a business that sells on deferred terms it is a way of raising money without pledging assets, but the price of that convenience, and the way the risk falls, depend on the terms of the particular contract.
What the new law changed
The main innovation is the Register of Assignments of Monetary Claims under Factoring Contracts. It works as a public database alongside the electronic factoring system and makes it impossible to sell the same claim to two factors at once. Before the register, double assignment was a real risk, and a buyer of a claim could check for it only by asking the counterparties.
The second change concerns prohibitions in the underlying contracts. A supplier whose contract said “assignment of claims without the buyer’s written consent is not permitted” was in practice shut out of factoring. Such terms are now void, meaning they need no court challenge and have no effect from the moment the contract was made. The law also excludes from its scope gratuitous assignments and claims whose performance date has already passed.
Who can be a factor, a client and a debtor
The factor is a financial services provider licensed for this business, including a non-resident authorised to provide factoring services. The non-bank financial services market is regulated by the National Bank of Ukraine, and checking a factor in its register takes a few minutes. That is the first thing to do before signing anything.
The client may be a company or a sole trader, so a private individual cannot assign a claim by way of factoring. The debtor is whichever party to the underlying contract has to pay. For existing market participants the law set a transition: finance companies notify the regulator within one month and bring their activity into line within six months, or lose the right to provide factoring services. Handling that procedure forms part of our factoring company registration service.
With or without recourse: where the risk sits
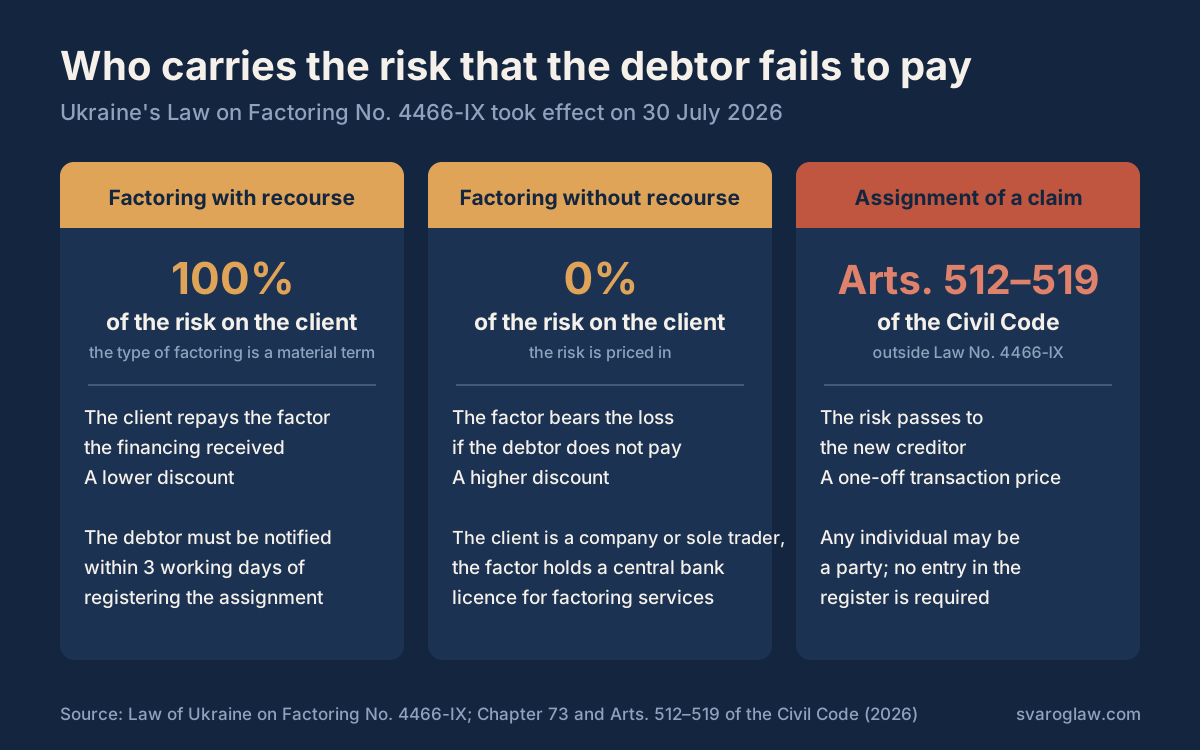
The type of factoring is an essential term of the contract, and it decides who loses the money if the debtor does not pay. Under a recourse contract the client must return a set sum to the factor where the debtor fails to perform on time. Non-recourse factoring shifts that risk to the factor, which is why its discount is always larger.
| Criterion | Recourse factoring | Non-recourse factoring | Assignment of a claim |
|---|---|---|---|
| Who loses out if the debtor does not pay | the client repays the factor | the factor; the risk is priced in | the new creditor |
| Price to the client | lower discount and commission | higher discount reflecting the risk | a negotiated price for a one-off deal |
| Who can be a party | a licensed factor; the client a company or sole trader | a licensed factor; the client a company or sole trader | anyone, including private individuals |
| Provision | Law No. 4466-IX, Chapter 73 of the Civil Code | Law No. 4466-IX, Chapter 73 of the Civil Code | Arts. 512–519 of the Civil Code |
Confusion between factoring and assignment cost businesses a good deal of litigation, as courts reclassified one contract as the other and held deals invalid. A separate statute listing the essential terms closes that gap, but the wording of the particular contract still has to be checked. That analysis forms part of legal review and due diligence.
The register of assignments and notifying the debtor
Once the assignment is registered, the factor must notify the debtor within three working days, giving the payment details and the particulars of the claim. For the debtor this is critical: paying the old creditor after proper notice does not discharge the obligation to pay the factor. On receiving such a notice, check the entry in the register and only then change the payment details in your accounts.
The tax treatment of factoring is unchanged: subparagraph 196.1.5 of the Tax Code takes assignment and factoring operations outside the scope of VAT, with the exceptions listed in that subparagraph. The client treats the factor’s commission and the discount as expenses under the general rules.
How to enter a factoring contract without surprises
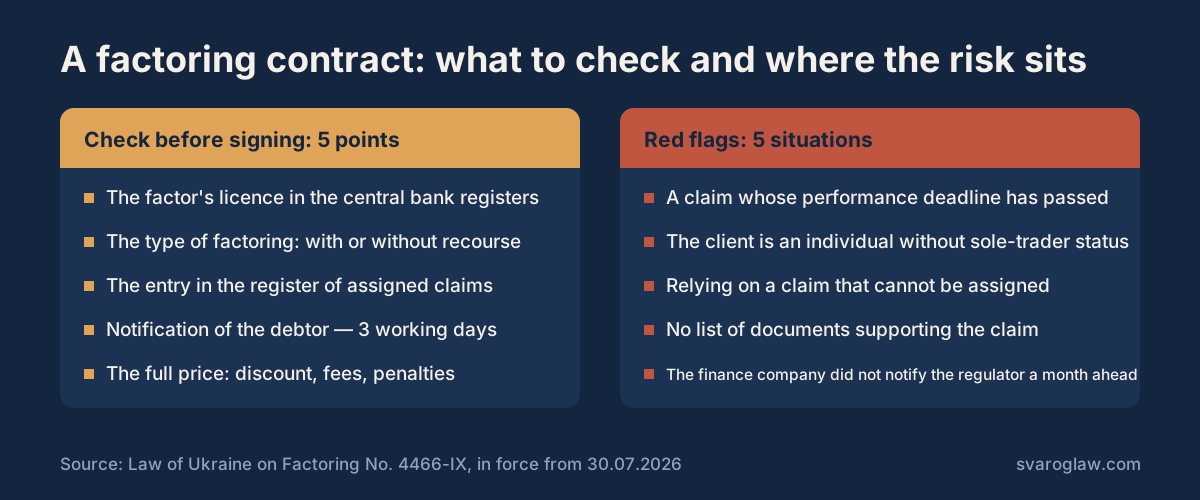
- Check the factor in the National Bank of Ukraine’s register and make sure it is entitled to provide factoring services specifically. A company without that right cannot lawfully register the assignment.
- State the type of factoring in the contract in plain words: “with recourse” or “without recourse”. Leaving it out makes the allocation of risk a matter for a future dispute.
- Work out the full price: the discount, the servicing commission, the charge for assessing the debtor and the penalties for late payment. Compare not the discount percentage but the final sum that reaches your account.
- Check the list of documents evidencing the claim and the deadlines for handing them to the factor. Contracts, delivery notes, acceptance certificates and invoices must be signed by the proper people, or the factor will refuse funding after signing.
- Make sure the assignment is registered and the debtor notified within three working days. Otherwise the payment goes to the old details and sorting it out falls to you.
- Agree what happens if the debtor is late: who negotiates, from what day penalties accrue, when recourse arises. These clauses are read last and applied most often.
Typical mistakes clients make
- Signing without noticing the recourse. The client believes the debt is sold for good, and three months later receives a demand to return the whole of the funding.
- Assigning a claim whose performance date has passed. The law puts such claims outside its scope, and the deal will not produce the legal result expected.
- Not checking the register before signing. If the claim has already been assigned to another factor, the second deal becomes a dispute between two finance companies with you in the middle.
- Ignoring a notice of assignment as the debtor. Paying the previous creditor after proper notice does not discharge the obligation to the factor.
- Relying on a no-assignment clause in the underlying contract. Such terms are now void, so they can no longer be counted on as protection against a change of creditor.
When you do not need a lawyer
A one-off deal for a modest sum with a bank using its own standard form and holding a spotless reputation usually needs no outside lawyer: an attentive accountant and a check of the register suffice. A notice of assignment can likewise be accepted and the details changed alone, once the register entry confirms it. A lawyer is needed where the sum matters to the company’s cash flow, where a standing factoring programme is being set up, or where the claim is already overdue and the deal is really a debt purchase rather than classic financing.
Questions and answers
From what date does the new factoring law apply?
Law No. 4466-IX was passed on 3 June 2025, took effect on 30 July 2025 and came into operation on 30 July 2026. Contracts made before it came into operation are governed by the rules in force when they were made.
Can a private individual assign their debt under a factoring contract?
The client under a factoring contract may be a company or a sole trader. A citizen without that status is left with an ordinary assignment of a claim under Articles 512–519 of the Civil Code.
Is the debtor’s consent needed for factoring?
No consent is required, and terms of the underlying contract prohibiting assignment are void. The debtor is merely notified of the assignment within three working days of its registration.
What is recourse factoring in plain terms?
It is funding under which the client answers to the factor if the buyer does not pay on time. The client must return the sum the contract specifies, which is why the discount is lower than on a non-recourse deal.
Is factoring subject to VAT?
Subparagraph 196.1.5 of the Tax Code takes assignment and factoring operations outside the scope of VAT, with the exceptions it lists. A particular transaction is worth checking with your accountant.
How do I check whether a company may provide factoring?
Check it in the registers of the National Bank of Ukraine, which regulates the non-bank financial services market. The right to provide factoring must appear expressly among its permitted services.
What should a debtor do on receiving a notice of assignment?
Match the notice against the entry in the Register of Assignments of Monetary Claims and confirm that the claim really has been transferred. Once confirmed, change the payment details, since paying the old creditor will not discharge you.
How does factoring differ from a loan?
The funding is advanced against a monetary claim on a third party rather than against a pledge of assets, and is repaid out of the debtor’s payment. How much is advanced depends on the quality of the receivables, not on the client’s collateral.
What does legal support for a factoring deal cost?
At Svarog a consultation costs from 1,500 UAH, drafting the contract from 5,000 UAH, a written legal opinion from 5,000 UAH and full handling of a commercial case in court from 30,000 UAH. Current rates are on the page of legal service prices.
Can a future monetary claim be assigned?
Assignment of future claims is used in factoring, but the claim must be defined or capable of identification when it arises. The wording of the subject matter is decisive here.
Sources
- Law of Ukraine “On Factoring” No. 4466-IX — zakon.rada.gov.ua
- Civil Code of Ukraine, Arts. 512–519 and Chapter 73 on factoring — zakon.rada.gov.ua
- Law of Ukraine “On Financial Services and Finance Companies” No. 1953-IX — zakon.rada.gov.ua
- Tax Code of Ukraine, subparagraph 196.1.5 — zakon.rada.gov.ua
- National Bank of Ukraine, registers of financial services providers — bank.gov.ua
Factoring transactions with Svarog
We check the factor’s status and the entry in the register of assignments, read the contract against the particular deal, settle the type of factoring and the final price, prepare the documents for registering a factoring company and run disputes with debtors. If a draft contract or a notice of assignment has just arrived, send it to us before you sign or change any payment details. A consultation costs from 1,500 UAH and drafting the contract from 5,000 UAH; bank factoring support is priced by the size of the transaction.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00