Олександр Сич
10 April 2026
The State Tax Service must give notice of a scheduled documentary audit at least 10 calendar days in advance, serving a copy of the order and a written notification. The audit itself lasts up to 30 working days for large taxpayers, up to 20 for ordinary ones and up to 10 for small businesses, and objections to the report are filed within 10 working days.
The State Tax Service published the schedule of documentary audits for 2026 on 24 December 2025 and updated it several times during the year. You can check whether you are on it free of charge on the service’s website, and that is where preparation starts: a business that is not on the schedule faces no scheduled audit this year.
Preparing for an audit has little to do with tidying up the day before the inspectors arrive. It comes down to three things: knowing your deadlines, having the last 1,095 days of documents in a fit state to be examined, and understanding which of the tax officers’ steps can lawfully be stopped at the door.
The kinds of audit, and which comes with notice
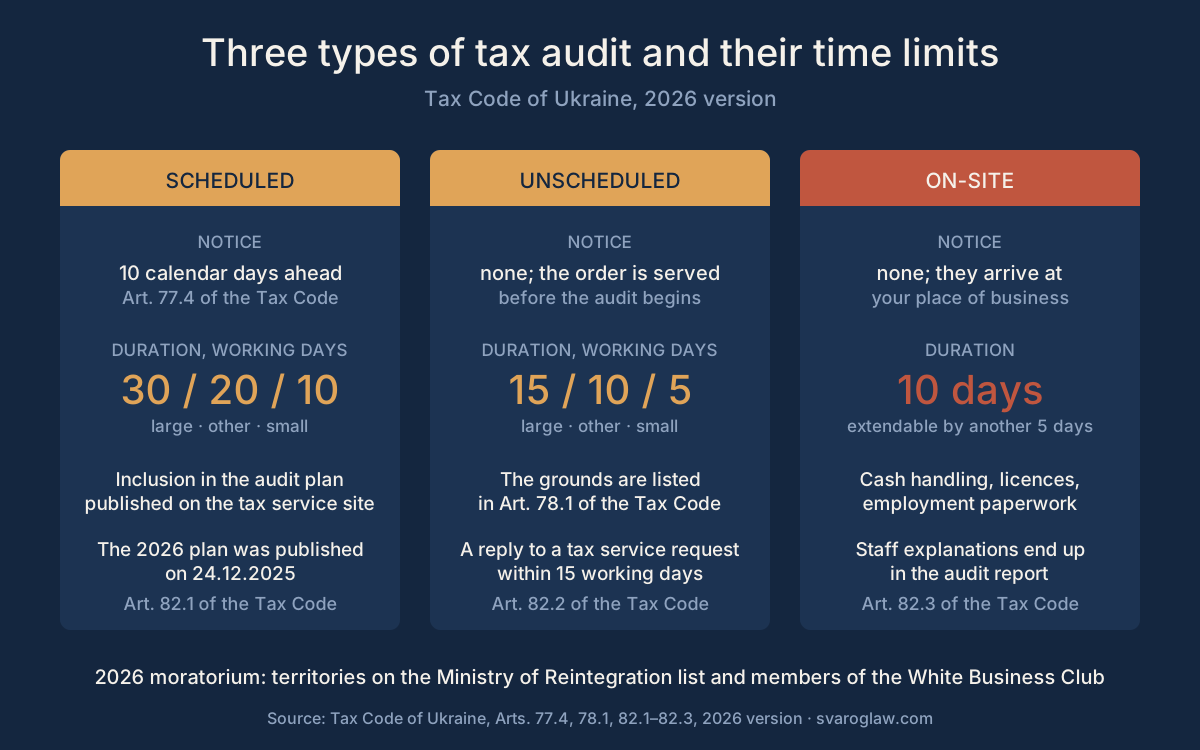
A desk audit is carried out at the tax office on the basis of the returns filed, and the taxpayer is not notified at all. A scheduled documentary audit is on the published schedule, and it is the one requiring 10 calendar days’ notice under paragraph 77.4 of the Tax Code. An unscheduled documentary audit is ordered on the grounds in paragraph 78.1, which include failing to file returns, failing to answer a request, and discrepancies found in counterparties’ tax reporting.
A factual audit concerns cash handling rules, licences, the formal employment of staff and till discipline. It is carried out without notice at the place where business is actually done, lasts no more than 10 days and may be extended by 5 more. Factual audits are the ones that most often take retailers and caterers by surprise.
Who is not audited in 2026
The moratorium on scheduled audits continues in 2026 for taxpayers whose tax address lies in the territories on the list approved by the Ministry for Reintegration — temporarily occupied territories and areas of active or possible hostilities. The second exception covers those on the list of taxpayers with a high level of voluntary tax compliance, better known as the White Business Club: scheduled documentary audits are not applied to them.
Unscheduled audits on certain grounds go ahead even during the moratorium, so a business that is clear of the schedule can still get a visit because of a request about a counterparty. Where the tax authority sends a written request, the answer must be given within 15 working days: silence is itself a ground for an unscheduled audit under paragraph 78.1.
Deadlines worth keeping in front of you
| Stage | Deadline | Tax Code provision |
|---|---|---|
| Notice of a scheduled audit | at least 10 calendar days before it starts | paragraph 77.4 |
| Duration of a scheduled audit | 30 working days for large taxpayers, 20 for others, 10 for small businesses | paragraph 82.1 |
| Duration of an unscheduled audit | 15 working days for large taxpayers, 10 for others, 5 for small businesses | paragraph 82.2 |
| Factual audit | 10 days, extendable by 5 | paragraph 82.3 |
| Drawing up and registering the report | 5 working days after the audit ends | paragraph 86.3 |
| Objections to the report | 10 working days from the day after it is received | paragraph 86.7 |
| Tax assessment notice | 15 working days | paragraph 86.8 |
| Complaint to the State Tax Service of Ukraine | 10 working days from receiving the decision | paragraph 56.3 |
| Claim to the administrative court | 6 months, or 1 month after an administrative complaint | Supreme Court Grand Chamber, July 2025 |
Preparing for an audit, step by step
- Check the schedule on the State Tax Service’s website and save a dated screenshot of the page. If the business was added during the year, your preparation time runs from the date of that update.
- Bring the primary documents into line with the registers for the last 1,095 days. That is the retention period set by paragraph 44.3, and failing to keep documents carries a fine of 1,020 UAH, or 2,040 UAH for a repeat breach within a year.
- Run an internal audit of the risky transactions: deals with counterparties labelled risky, transactions with no goods behind them, adjustments to the VAT credit, payments made without formal employment. It is better to find the problem yourself and correct the returns before the audit.
- Write an instruction for staff with one key rule: only an authorised person hands over documents or gives explanations. Security, the accounts department and sales staff each need their own note, because it is their words that end up in the factual audit report.
- Appoint someone by order to handle the audit and issue a power of attorney. If you are bringing in an outside adviser, do it before the start date, not after the report is served.
- Set aside a separate room for the inspectors and keep the audit register. Hand over copies on a written request with an inventory, keeping the signed second copy of that inventory yourself.
Refusing entry: when it is lawful
Paragraph 81.1 of the Tax Code gives an exhaustive list of grounds for refusing officials entry to an on-site documentary or factual audit: failure to produce or send the audit authorisation, a copy of the order and service identification, or those documents being drawn up in breach of the requirements. There are no other lawful grounds.
The consequence is serious: the authority becomes entitled to place an administrative attachment on the taxpayer’s property under Article 94. So a decision to refuse entry is taken only where the defect in the documents is obvious and has been recorded in writing in the audit register with signatures. A tax disputes lawyer can assess that risk within a few hours.
What happens after the audit
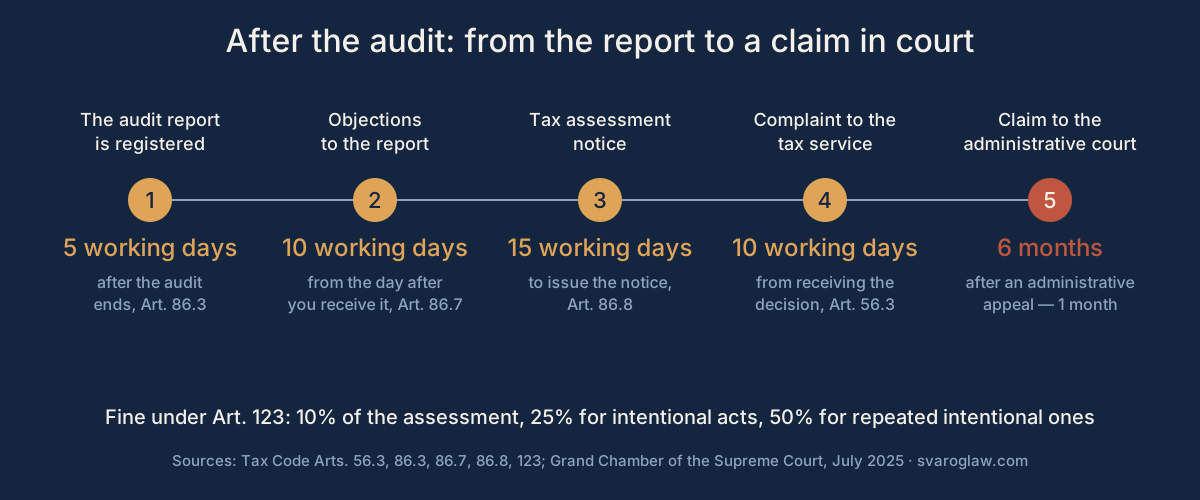
The report is registered within 5 working days of the audit ending and served on the taxpayer. The law allows 10 working days for objections, and that document has real value: arguments not raised in the objections later have to be explained to a court, which asks why they appeared only in the claim. The assessment notice is issued within 15 working days, or, where objections were filed, after they are considered.
Penalties are calculated on the assessed sum: the base rate under Article 123 is 10 %, rising to 25 % for deliberate acts and 50 % for repeated deliberate acts within 1,095 days. Then comes the choice: pre-trial settlement of tax disputes through a complaint to the service’s central office, or a claim straight to the administrative court. One detail from recent years matters: after an administrative complaint only one month remains for the claim, and missing it closes the door to the court.
Typical mistakes taxpayers make
- Handing over original documents. The law allows certified copies, and originals are seized only in the cases it expressly provides for, so handing them over “for convenience” leaves you without your evidence.
- Letting any employee give explanations. Circumstances recorded from a shop assistant’s words end up in the factual audit report and can then be rebutted only in court.
- Not filing objections to the report, counting on winning in court. That is a wasted stage at which part of the assessment is often removed without the cost of litigation.
- Confusing the deadlines. Ten working days for the complaint and one month for the claim after an administrative complaint are counted in different units, and that is where deadlines are most often missed.
- Refusing the inspectors entry without formal grounds. Instead of buying time the business gets an administrative attachment on its property and a damaged position in the dispute to come.
When you do not need a lawyer
A desk audit in which the tax authority asks about a discrepancy of a few thousand hryvnia is dealt with by the accountant, with a written answer and copies of the documents. A scheduled audit of a small business with transparent operations, clean primary documents and no risky counterparties likewise needs no lawyer. It is worth bringing in a defence where the assessment exceeds the cost of representation, where the issue is whether business transactions were real, or where the case is plainly heading towards challenging tax assessment notices.
Questions and answers
How much notice is given of a tax audit?
A scheduled documentary audit is notified at least 10 calendar days before it starts, with a copy of the order and a written notification. Unscheduled and factual audits need no notice.
How do I find out whether my business is on the 2026 audit schedule?
The schedule is on the State Tax Service’s official web portal; it was published on 24 December 2025 and is updated during the year. The search is free and needs only the registration code.
How long can a scheduled audit last?
Up to 30 working days for large taxpayers, up to 20 for other taxpayers and up to 10 for small businesses. Those periods may be extended by 15, 10 and 5 working days respectively.
Can the tax authority be refused entry to a business?
There are only three lawful grounds: you were not shown the audit authorisation, the copy of the order or the service identification, or those documents were drawn up defectively. Refusing entry without such grounds opens the way to an administrative attachment on your property under Article 94.
How long must primary documents be kept?
The general period is 1,095 days from filing the return in which the documents were used. Failing to keep them carries a fine of 1,020 UAH, or 2,040 UAH for a repeat breach within a year.
What penalty follows an additional assessment?
Article 123 sets 10 % of the liability determined, 25 % for deliberate acts and 50 % for repeated deliberate acts within 1,095 days. Those percentages are charged on top of the assessed sum itself.
How long is there to challenge a tax assessment notice?
A complaint to the State Tax Service of Ukraine goes in within 10 working days, and a claim to the administrative court within 6 months. If you complained administratively first, one month remains for the claim.
Is the audit moratorium in force in 2026?
The moratorium continues for taxpayers in temporarily occupied territories and areas of active or possible hostilities, and for members of the White Business Club. Other businesses are audited under the general rules.
Can original documents be handed to the inspectors?
Provide properly certified copies with an inventory in two counterparts. Originals may be seized only in the cases the law expressly provides for.
What does handling a tax audit cost?
At Svarog a consultation costs from 1,500 UAH, a written legal opinion from 5,000 UAH, pre-trial settlement from 5,000 UAH and full handling of an administrative case from 30,000 UAH. Current rates are on the page of legal service prices.
Sources
- Tax Code of Ukraine, Arts. 44, 75–86, 94, 123, 124 — zakon.rada.gov.ua
- Administrative Procedure Code of Ukraine, Art. 122 — zakon.rada.gov.ua
- The schedule of documentary audits and the list of taxpayers with a high level of voluntary tax compliance — tax.gov.ua
- List of territories where hostilities are or were taking place, or which are temporarily occupied — zakon.rada.gov.ua/laws/show/z0380-25
- Unified State Register of Court Decisions — reyestr.court.gov.ua
Handling a tax audit with Svarog
We check that the order and the authorisation are lawful before the audit even begins, handle the dealings with the inspectors, and prepare the objections to the report, the complaint to the service’s central office and the claim to the administrative court. If the report has already been served, call in the first few days: the ten working days for objections run out fast, and after that the options narrow. A consultation costs from 1,500 UAH and full handling of an administrative case from 30,000 UAH; our administrative cases practice covers every level of court.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00