Олександр Сич
4 October 2026
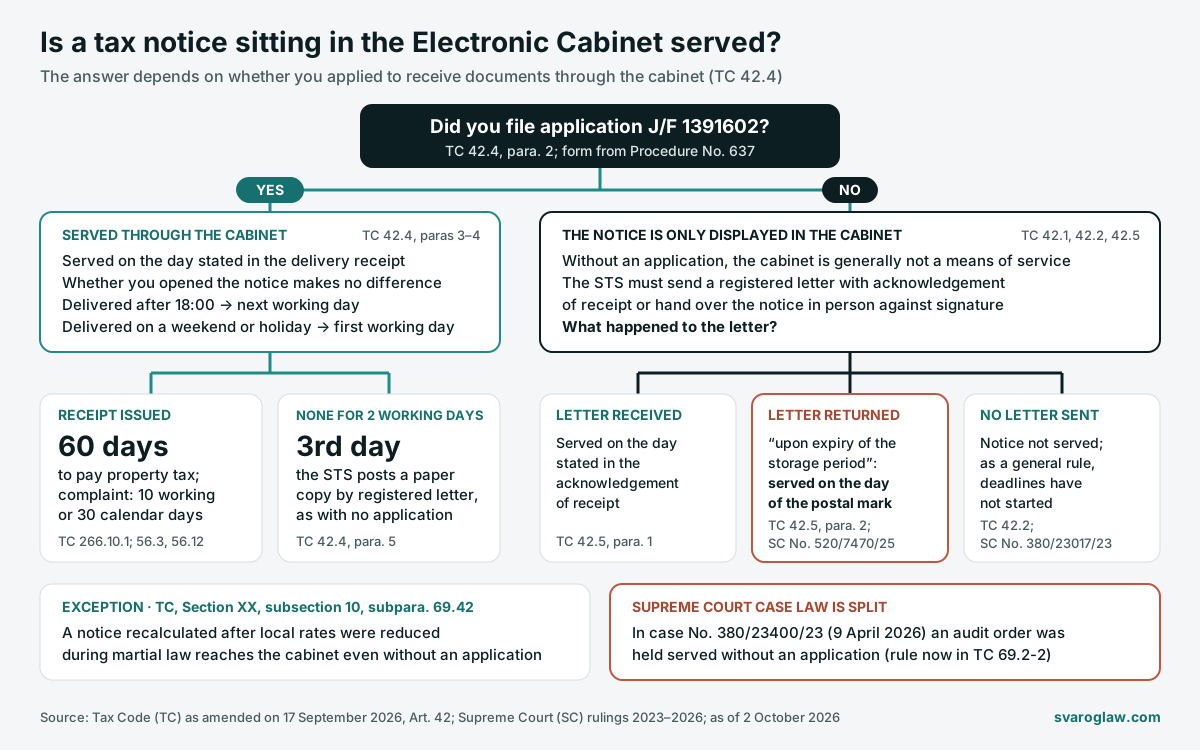
No, provided you have not filed an application with the State Tax Service (STS) to receive documents through the Electronic Cabinet (the STS taxpayer portal): in that case, as a general rule, a tax assessment notice is only displayed in the Electronic Cabinet, and the STS had to serve it by registered letter with acknowledgement of receipt or in person (paragraph 42.5 of the Tax Code, or TC). If you did file such an application at some point, the notice is deemed served on the day stated in the delivery receipt, even if you never opened it (TC 42.4, paras 3–4). The 60 days to pay property tax and the deadline for a complaint both run from the date of service, so find out that date first, and only then decide whether to pay or challenge the notice.
The familiar logic of “I didn’t open it, so it wasn’t served” is only half right. By law, tax office documents must be displayed in the cabinet (TC 42.1), so the notice should be visible there even to those who have not filed the application, but for them, as a general rule, this does not yet count as service. They are most likely the majority: in 2025 more than 3.1 million taxpayers used Electronic Cabinet services, while as of 1 December 2025 there were 429,122 applications to receive documents through the cabinet (STS Main Department in Chernihiv Region, 18 December 2025). The two figures were counted on different bases, but the gap is more than sevenfold.
A tax assessment notice in the Electronic Cabinet: have you filed the application or not?
The notice is served as soon as it becomes available in the cabinet, and the date is set by the automatic delivery receipt (TC 42.4, paras 3–4). Whether you opened the document makes no difference. At the same time, the STS must send a letter to your e-mail stating the type of document and the date and time it was sent (TC 42.4, para. 2).
The notice is only displayed in the cabinet. It can be served by registered letter with acknowledgement of receipt sent to your tax address, or in person against signature (TC 42.2; 42.5, para. 1), and until that happens, as a general rule, the deadlines for payment and for a complaint do not start running. The STS itself admits in its explanation of 29 July 2026 that a document can be served through the cabinet only after such an application.
There is an exception for local taxes, and it concerns decisions adopted during martial law or before 31 December of the year in which martial law is lifted. If a local council or military administration reduced rates by such decisions (including through reliefs), the recalculated notice arrives in the cabinet even without an application, with the date of service set by the receipt (TC, Section XX, subsection 10, subparagraph 69.42; Law No. 4536-IX of 16 July 2025).
How to find out whether the notice has already been served on you
- Find out whether you filed the application. It is form J/F 1391602, and once it has been filed the STS sends receipts No. 1 and No. 2 (STS Main Department in Kyiv Region, 19 August 2025). If you have no receipts and do not remember filing it, ask the tax office where you are registered.
- Find the delivery date. The cabinet records the date and time of every document with a qualified electronic time stamp and lets you download this data as a receipt (TC 42-1.1, para. 9). You are entitled to view the event log (Section II, item 20 of Procedure No. 637). In a dispute, demand the receipt itself from the STS: for form “Ф” (F) notices, including property tax notices, it is attached to the counterfoil (Section III of Procedure No. 1204).
- Check the time and the day. A document delivered after 18:00 is deemed served on the next working day, and one delivered on a weekend or public holiday, on the first working day after it (TC 42.4, para. 4).
- Check the inbox of the e-mail address given in the application. The letter about the document is mandatory, and in court the tax office has to prove that it sent it (Supreme Court ruling in case No. 280/923/23; Code of Administrative Procedure, Art. 77(2)).
- No receipt for 2 working days? Then on the 3rd working day the STS must send a paper copy by registered letter with acknowledgement of receipt or hand it over in person (TC 42.4, para. 5), and from then on the date of service is set by the post office.
- No application filed? Look for the letter. The post office records the date in the acknowledgement of receipt. If the letter was not handed to the addressee, the notice is deemed served on the day the post office entered next to the reason for non-delivery (TC 42.5, para. 2).
A hypothetical example: you did file the application, and the receipt shows that the notice was delivered on Friday at 19:10. Service moves to Monday, provided it is a working day. The deadline for a complaint (10 working days after the day of receipt, TC 56.3, para. 1) starts running on Tuesday, even if you never logged in to the cabinet.
The post office can also “serve” it without you. If the letter was sent to your tax address as recorded in the register, sat at the post office and was returned “upon expiry of the storage period”, the notice is deemed served on the day of the post office’s mark (TC 42.5, para. 2). This is how the Supreme Court ruled, for example, in cases No. 420/20746/24 (6 November 2025, property tax) and No. 520/7470/25 (13 November 2025). In the second case the notice was deemed served back in August 2024, the sole proprietor (FOP) went to court only in March 2025, and the claim was left without consideration. To the arguments about postal disruptions during the war, the court replied that the claimant “has the right to file an application expressing the wish to receive documents through the electronic cabinet”.
Which deadlines run from the date of service
| Action | Deadline | Provision |
|---|---|---|
| Payment of property tax by an individual | 60 days from the day of service | TC 266.10.1(a) |
| Payment under a notice issued on the grounds in TC 54.3.1–54.3.6 (mostly after audits) | 10 working days after the day of receipt | TC 57.3, para. 1 |
| Complaint to the State Tax Service of Ukraine | 10 working days after the day of receipt | TC 56.3, para. 1 |
| Complaint against a notice not issued for a violation (including property tax) | 30 calendar days | TC 56.12 |
| Court claim | 6 months without a complaint, or 1 month after the appeal procedure ends | Code of Administrative Procedure, Art. 122(2); TC 56.19; Grand Chamber of the Supreme Court, No. 500/2276/24 |
Even with property tax, it is safer to file within 10 working days: this is the deadline to which TC 56.15 links the suspension of payment while the appeal is pending. A complaint to the State Tax Service of Ukraine is free of charge, so pre-trial settlement of tax disputes usually makes more sense than going straight to court. If the deadlines have passed and the STS relies on the cabinet even though you never filed the application, the dispute over service becomes the core of challenging tax assessment notices in court.
If the STS has done everything required for service, it does not matter whether you saw the notice. In the Supreme Court’s words, whether a tax liability has become agreed “is linked not to the person’s physical receipt of tax assessment notices, but to the tax authority taking all the steps necessary to serve such decisions” (case No. 420/35624/23, 29 April 2025). The STS must send a property tax notice by 1 July of the year following the reporting year (TC 266.7.2); otherwise you are released from liability for late payment, although the tax itself remains due (TC 266.10.2, 266.10.3). And if the notice came for an apartment you have already sold, reconcile the charge first: we explained how to do this without going to court in our article on a tax notice for an apartment you no longer own.
How the Supreme Court rules
A telling example is case No. 380/23017/23. Scholz Utilizator AG LLC had not filed the application, and the tax office sent the audit order and the audit notification only to the cabinet. The first-instance court found that a screenshot from the STS’s internal system did not prove delivery and set aside the notice issued after the audit. The court of appeal sided with the STS, but the Supreme Court quashed its ruling and upheld the judgment in the taxpayer’s favour:
“In the absence of such an application, the supervisory authority must send the relevant documents to the taxpayer in the manner established by paragraph 42.5 of Article 42 of the Tax Code of Ukraine” (Supreme Court ruling of 20 February 2025, case No. 380/23017/23).
The case concerned an audit order, not a notice, but Art. 42 of the Tax Code sets the same service rules for all tax office documents. We therefore believe the conclusion applies to notices too, and that it is the STS that has to prove service in court (Code of Administrative Procedure, Art. 77(2)).
The Supreme Court has followed this line since 2023:
- No. 380/7418/22 (6 July 2023): the source of the formula the court still repeats, “the precondition for the supervisory authority’s use of the method of correspondence … is the taxpayer’s filing of the relevant application”.
- No. 280/923/23 (9 May 2024): proof of delivery is “only a delivery receipt in text format”, and photos of a screen do not prove receipt.
- No. 380/11112/23 (23 October 2024): in a dispute with a sole proprietor, screenshots with empty “received” and “receipt” fields did not prove receipt.
- No. 520/18946/23 (5 May 2025): without an application, the STS had no grounds to send documents to the sole proprietor’s cabinet, but the court held that letters returned by the post office had been served.
- No. 160/14765/24 (23 December 2025): the case of PJSC Dniprovskyi Metallurgical Plant was sent back for a new hearing, partly because the courts had not established whether an application had been filed.
- No. 620/8115/25 (18 August 2026): printouts showing that documents were sent to the cabinet, without a receipt, do not prove the date of service.
There is also an opposing line: on 9 April 2026 a panel of the Supreme Court in the Lemberg Park LLC case (No. 380/23400/23) held that an audit order sent to the cabinet without an application had been served. The court relied on the wartime rule (then paragraph 69.2, now subparagraph 69.2-2 of subsection 10 of Section XX of the Tax Code) and on the fact that the taxpayer had ignored its obligations. The subparagraph concerns audits, but its last sentence is general: a document sent to the electronic cabinet “is deemed served on the taxpayer”, and there is no mention of an application.
As of 2 October 2026 we have not found a ruling by a judicial chamber or the Grand Chamber that resolves this divergence. Nor have we found a ruling on an individual without sole proprietor status whose property tax notice was simply placed in the cabinet. For businesses the risk is greater, because the lawfulness of the entire audit depends on whether the audit order was served. We wrote about the deadlines after an audit in our overview of legal support in tax disputes.
How to apply for electronic correspondence and how to withdraw
You log in to the cabinet with a qualified electronic signature, via id.gov.ua (MobileID, BankID), with Diia.Signature or with a cloud-based qualified electronic signature. Then:
- Via settings: “Налаштування” (Settings) → “Бажання листування з КО” (Correspondence with the supervisory authority) → “Бажаю отримувати документи” (I wish to receive documents) → e-mail → signature (STS Main Department in Ivano-Frankivsk Region, 12 February 2026).
- Via reporting: “Введення звітності” (Report entry) → “Створити” (Create) → “F(J) 13 Запити” (F(J) 13 Requests) → form J/F 1391602 → e-mail → qualified electronic signature.
- Withdrawal: form J/F 1391702, no more than once a year. Correspondence through the cabinet stops from the date of the delivery receipt for this application (TC 42.4, para. 7; Section II, item 21 of Procedure No. 637).
If you live abroad or your post is unreliable, the application can help you avoid what happened in case No. 520/7470/25: the notice will arrive in the cabinet, and a message about it will arrive by e-mail. But if you only log in to the cabinet once every few months, with the application in place the 10 working days for a complaint may run out before you even see the notice. We recommend filing the application only if you really do read the mail at the e-mail address you give and check the cabinet at least once a week.
You can file the application or withdraw it on your own. But if the STS is already counting deadlines from a notice you have never seen, or relies on the cabinet even though you never filed the application, show the receipts and postal marks to our tax dispute lawyer. They will check the dates and tell you whether the notice can still be challenged despite the missed deadline.
What this answer is based on
- Tax Code of Ukraine: Art. 42, paragraph 42-1.1, Arts 56, 57, subparagraph 266.7.2, paragraph 266.10, subparagraphs 69.2-2 and 69.42 of subsection 10 of Section XX (as amended on 17 September 2026) — zakon.rada.gov.ua; Code of Administrative Procedure, Arts 77, 122 — zakon.rada.gov.ua
- Procedure for the Functioning of the Electronic Cabinet, Ministry of Finance Order No. 637 of 14 July 2017 — zakon.rada.gov.ua; Procedure for Sending Tax Assessment Notices by Supervisory Authorities, Ministry of Finance Order No. 1204 of 28 December 2015 — zakon.rada.gov.ua
- Supreme Court rulings: No. 380/23017/23 (court register), No. 380/7418/22 (court register), No. 280/923/23 (court register), No. 380/11112/23 (court register), No. 520/18946/23 (court register), No. 160/14765/24 (court register), No. 620/8115/25 (court register), No. 380/23400/23 (court register), No. 520/7470/25 (court register), No. 420/20746/24 (court register), No. 420/35624/23 (court register), No. 320/40600/23 (court register), Grand Chamber No. 500/2276/24 (court register)
A paper copy within 3 working days and other questions
The notice was served through the cabinet. Can I get a paper copy?
Yes, the STS must issue one within 3 working days of your request (TC 42.5, para. 3). But the deadlines run from the date in the receipt, so file your complaint without waiting for the paper copy.
I am a sole proprietor and file my reports electronically. Isn’t that consent to correspondence through the cabinet?
Not in itself: electronic reporting or identification in the cabinet only makes it possible to correspond with the STS electronically (TC 42.4, para. 1), while service through the cabinet, as a general rule, starts with a separate application. There are a few exceptions. Decisions on complaints against a refusal to register a tax invoice or an adjustment calculation are sent only electronically, and the taxpayer’s wishes “have no legal significance” here (TC 56.23.5; case No. 320/40600/23). A notice recalculated after local tax rates were reduced arrives in the cabinet even without an application (TC, Section XX, subsection 10, subparagraph 69.42). And in case No. 380/23400/23 a panel of the Supreme Court held that an audit order sent only to the cabinet had been served without an application, relying on the wartime rule (now TC, Section XX, subsection 10, subparagraph 69.2-2). So if you are facing an audit, do not count on the fact that you never filed the application.
I found out about the notice late. Can the deadline for a complaint be reinstated?
Within 6 months after the deadline has expired, you can file a complaint together with a request for reinstatement and evidence of good reasons (TC 56.3, para. 3). A stronger argument is that the notice was never properly served at all: in that case, as a general rule, the deadline has not yet started. Postal disruptions during the war, however, were not accepted as a good reason for missing the deadline to go to court in case No. 520/7470/25. A claim to cancel the notice is filed with the district administrative court, and in such administrative cases the date of service is the first issue.