
Олександр Сич
9 April 2026
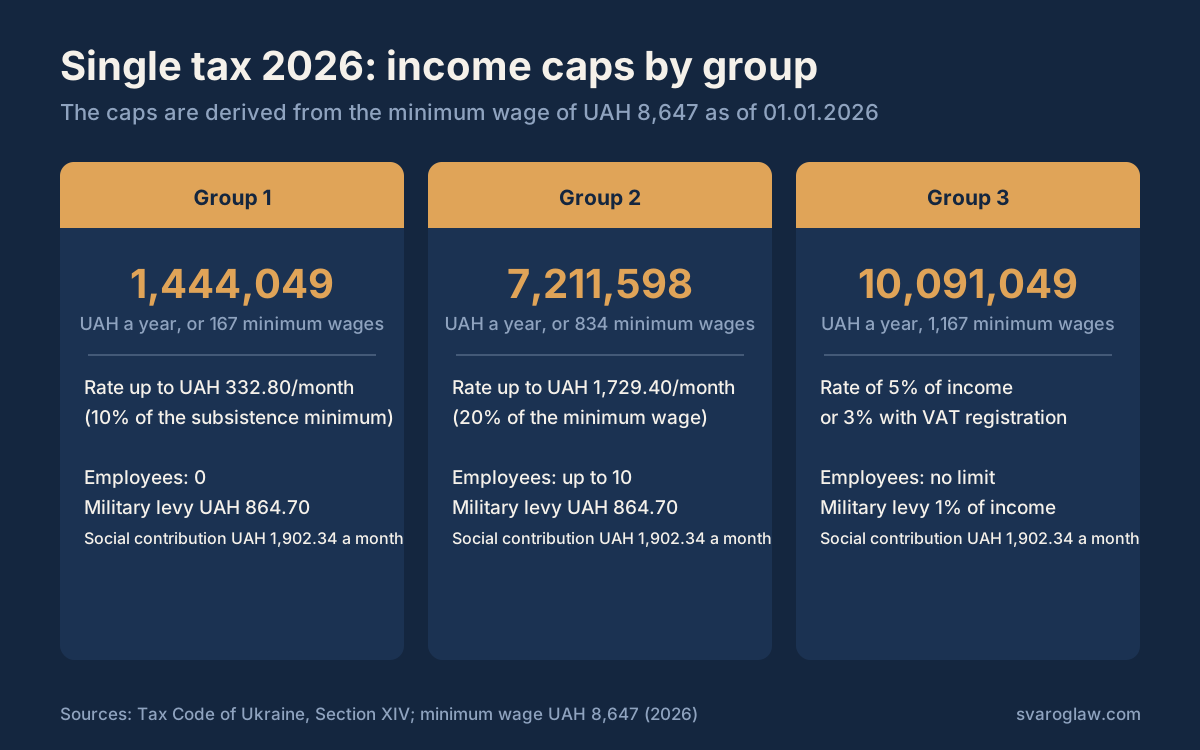
In 2026 the annual income cap is 1,444,049 UAH for group 1 of the single tax, 7,211,598 UAH for group 2 and 10,091,049 UAH for group 3. The group 3 rate is 5 % of income without VAT, or 3 % with VAT registration. On the general system an entrepreneur pays 18 % of net income plus a 5 % military levy.
From 1 January 2026 the minimum wage is 8,647 UAH, and it is from that figure that the Tax Code calculates the income caps for single tax payers: 167 minimum wages for group 1, 834 for group 2 and 1,167 for group 3. The subsistence minimum for working-age people, 3,328 UAH, sets the group 1 rate.
Choosing between the simplified and the general system is not a question of privileges but of arithmetic. It depends on what share of revenue your costs take, on who your customers are, and on your line of business, since for some sectors the simplified system is closed entirely. Below are the 2026 figures, the limits of each system and how to switch; if matters have already reached a dispute with the tax authority, that is handled by our tax disputes lawyer.
Single tax caps and rates in 2026
Group 1 is for entrepreneurs with no employees who trade in markets or provide household services to the public. Group 2 allows up to ten employees, but the customer base is limited to individuals and other single tax payers, so a group 2 entrepreneur cannot work with a company on the general system. Group 3 is the most flexible: no limits on staff numbers or on who the customers are.
Exceeding the cap does not end the right to the simplified system instantly, but the excess is taxed at 15 %, and the taxpayer must move to another group or to the general system from the next quarter. Under paragraph 291.6 settlements must be exclusively in money: barter, set-off of mutual claims and promissory notes all forfeit the right to the simplified system.
| Indicator | Group 1 | Group 2 | Group 3 | General system, sole trader |
|---|---|---|---|---|
| Annual income cap | 1,444,049 UAH | 7,211,598 UAH | 10,091,049 UAH | no limit |
| Tax rate | up to 332.80 UAH a month | up to 1,729.40 UAH a month | 5 % of income, or 3 % with VAT | 18 % of net income |
| Military levy | 864.70 UAH a month | 864.70 UAH a month | 1 % of income | 5 % of net income |
| Employees | not allowed | up to 10 | no limit | no limit |
| Deduction of costs | not available | not available | not available | reduces the tax base |
What is paid on top of the tax itself
The unified social security contribution is the same for every group and every system: the minimum contribution in 2026 is 1,902.34 UAH a month, that is 22 % of the minimum wage. It is paid quarterly, and exemption applies only to old-age pensioners, people with disabilities and entrepreneurs whose employer pays the contribution for them at their main job.
Since 2025 the military levy has been a separate payment for entrepreneurs. For groups 1, 2 and 4 it is a fixed 864.70 UAH a month, that is 10 % of the minimum wage; for group 3 the rate is 1 % of income received, and on the general system 5 % of net taxable income. All told, the minimum burden on a group 1 sole trader in 2026 is about 3,099.84 UAH a month even with no income at all.
Who is barred from the simplified system
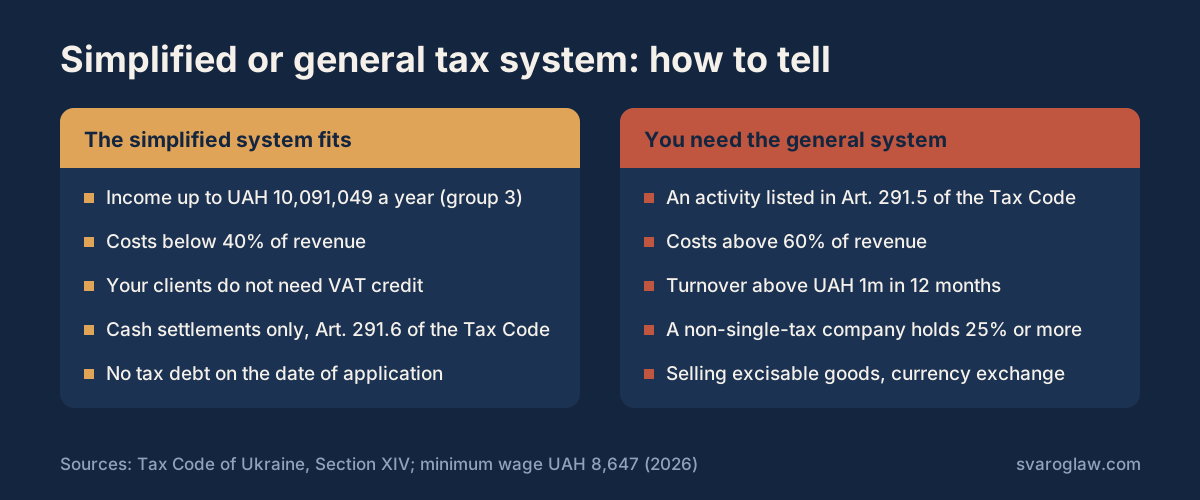
Paragraph 291.5 of the Tax Code contains a closed list of activities incompatible with the single tax. It covers organising gambling and lotteries, currency exchange, producing and selling excisable goods with narrow exceptions for retail, extracting and selling minerals, the business of insurance intermediaries, banks and credit unions, managing enterprises, postal and communications services, dealing in works of art and antiques, and organising art auctions.
Other prohibitions attach to the taxpayer’s status: the simplified system is closed to non-residents, to companies 25 % or more of whose charter capital belongs to legal entities that are not single tax payers, and to entrepreneurs with tax arrears on the day of the application. Breaching any of these means retrospective cancellation of single tax payer registration and assessment under the general rules; such decisions are challenged through challenging tax assessment notices.
When the general system is better
The general system works on the difference between income and documented costs under Article 177, so it wins where costs exceed roughly 60 % of revenue: in manufacturing, low-margin trade and construction. The rate is 18 % personal income tax and a 5 % military levy on net income, and a loss-making year produces no tax at all.
For limited liability companies the alternative is corporate profit tax at 18 % of the financial result. Paying dividends from such a company to an individual founder adds 5 % personal income tax and the military levy, so the total burden on money taken out has to be counted together rather than by one rate. Comparing the two structures for a particular business model forms part of legal review and due diligence.
VAT registration
The obligation to register for value added tax arises once taxable transactions over the last twelve calendar months exceed 1 million UAH: that threshold is set by paragraph 181.1. It applies both on the general system and to group 3 of the single tax, so crossing the million forces a choice between the 3 % rate with VAT and 5 % without.
Voluntary registration makes sense where your customers are themselves VAT payers and need the input credit: without it they effectively pay 20 % more. Where the customers are end consumers, registration only adds reporting and the risk of tax invoices being blocked.
How to switch systems
- Work out what share of revenue your costs took over the last twelve months: up to 40 % usually favours the simplified system, over 60 % the general one.
- Check your activity against paragraph 291.5 and against the activity codes in your register extract: a prohibited code blocks the switch even where you do not actually carry on that business.
- File the application for the simplified system no later than 15 calendar days before the next quarter begins.
- A newly registered entrepreneur choosing group 3 has a different deadline: 10 days from state registration.
- Clear any tax arrears before filing: their existence is a ground for refusal in itself.
- After the switch, check whether the million-hryvnia threshold over the previous twelve months makes VAT registration compulsory.
Typical mistakes in choosing a system
- Going by the outdated 5 million cap. The caps are recalculated each year from the minimum wage, and in 2026 group 3 stands at 10,091,049 UAH.
- Working in group 2 with companies on the general system. One such transaction forfeits the simplified system from the next quarter and brings 15 % tax on the whole sum.
- Accepting payment by barter or set-off. Paragraph 291.6 requires settlements exclusively in money.
- Registering activity codes “just in case” without checking the list in paragraph 291.5. A gambling or financial intermediation code in the register closes off the simplified system.
- Forgetting the social contribution in months with no income. The minimum 1,902.34 UAH accrues regardless of revenue, and underpayment turns into a debt with interest.
When you do not need a lawyer
An entrepreneur providing services to the public, earning up to half a million hryvnia a year and with no plans to hire, needs group 2 and an outsourced accountant, nothing more. The application for the simplified system is filed alone through the taxpayer’s electronic cabinet, free of charge. Legal help pays for itself in three situations: where the business structure involves several related parties, where the tax authority has already cancelled single tax payer registration, or where an audit has produced an assessment notice.
Questions and answers
What is the income cap for a sole trader in 2026
1,444,049 UAH for group 1, 7,211,598 UAH for group 2 and 10,091,049 UAH for group 3 per calendar year. The figures are calculated from the minimum wage of 8,647 UAH.
What does a group 3 sole trader pay
5 % of income as single tax without VAT, or 3 % with VAT registration, plus a 1 % military levy on income and 1,902.34 UAH a month in social contributions.
What happens if the single tax cap is exceeded
The excess is taxed at 15 %, and from the next quarter the entrepreneur moves to a higher group or to the general system. Single tax payer registration is cancelled where no switch is made.
How many employees may a single tax payer have
Group 1 may have none, group 2 up to ten at a time, and group 3 has no limit on staff numbers.
When can I switch from the simplified system to the general one
From the first day of any quarter, by filing the application no later than 15 calendar days before it begins. The reverse switch follows the same rule.
Can I be a single tax payer and work under an employment contract
Yes, the law does not forbid combining business with employment. If your employer pays social contributions for you at no less than the minimum, you are relieved of paying them for yourself.
At what turnover is VAT registration compulsory
At 1 million UAH of taxable transactions over the last twelve calendar months, under paragraph 181.1 of the Tax Code.
Which system suits an online shop
Where the margin is low and purchases are documented, the general system with cost deductions usually wins. With a high margin and end consumers, group 3 of the single tax comes out ahead.
Does a sole trader pay tax with no income
In groups 1 and 2, yes: single tax, military levy and social contributions accrue regardless of income. In group 3 the tax and levy are nil, but the 1,902.34 UAH contribution is still paid.
What if the tax authority has cancelled my simplified status
The decision is challenged administratively before the State Tax Service or in court. The ground for cancellation must be specific, and that is what is examined first.
Sources
- Tax Code of Ukraine, section XIV and paragraphs 181.1, 291.5, 291.6, 298.1.4, Art. 177
- Law of Ukraine “On the Collection and Accounting of the Unified Social Security Contribution”
- State Tax Service: single tax and military levy rates in 2026
- Taxpayer’s electronic cabinet: filing the application for the simplified system
- Unified State Register: checking activity codes
Choosing a tax system with Svarog
We calculate the tax burden under both systems on your own figures, check your activity codes against the simplified system, prepare the applications to switch and handle disputes with the tax authority. A consultation costs from 1,500 UAH, a written legal opinion from 5,000 UAH and full handling of an administrative case from 30,000 UAH; the remaining items are in our legal service prices.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00