Олександр Сич
7 April 2026
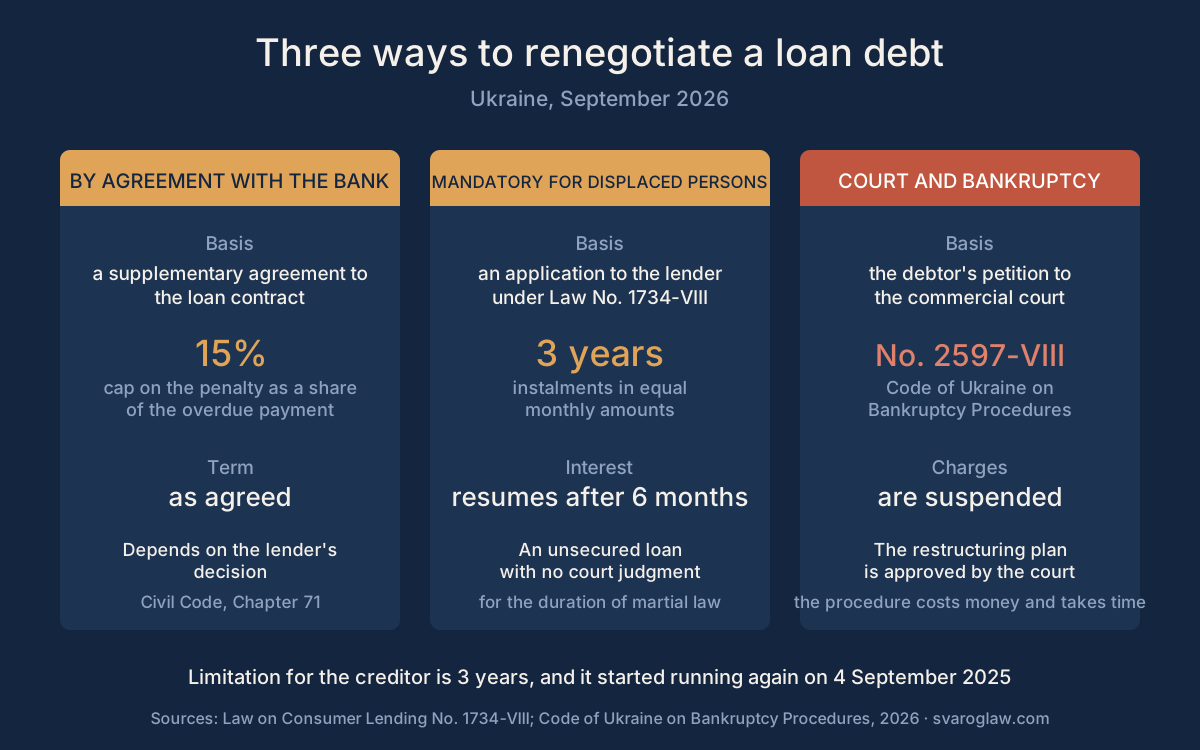
Restructuring does not reduce the debt by itself; it changes the schedule and the term for repaying it. For internally displaced people and residents of areas of hostilities the Law “On Consumer Lending” makes it compulsory: an unsecured loan is spread in equal instalments over three years, and the interest is paid within six months of martial law ending.
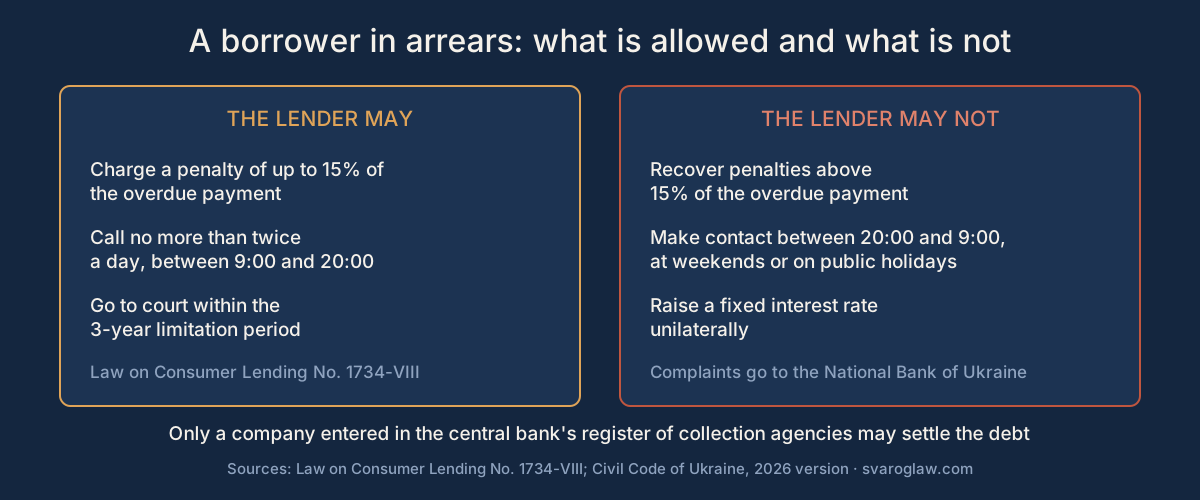
Penalties on a consumer loan are capped at twice the National Bank’s discount rate and may in no event exceed 15 % of the overdue instalment. That ceiling has existed since 2021, and it is what makes negotiating with a bank realistic: the lender knows the law will not let it grow the debt indefinitely through charges.
Restructuring means revising the terms of a live loan agreement by agreement between the parties. The term, the payment schedule, the monthly instalment and sometimes the currency or the rate can all change. A borrower deciding unilaterally to pay less is not restructuring and counts as a breach of contract, with all that follows.
What restructuring actually does, and what it does not
The main value of restructuring is that the instalment stops being unaffordable and arrears stop mounting. The bank usually extends the term, and the monthly payment falls, though the total cost over the whole period rises. Sometimes the lender grants a grace period in which the borrower pays interest only and the principal is left alone for a while.
Writing off part of the debt happens less often and almost always concerns the penalties and interest charged, while the principal stays as it was. Expect forgiveness of the principal only in exceptional circumstances such as the borrower’s serious illness, and the bank considers each such case on its own. The second practical benefit is the credit history: a restructured loan looks far better in the registers than one in arrears.
When the bank is obliged to agree
The general rule is uncomfortable for borrowers: voluntary restructuring is the lender’s right, not its duty. The exception comes from the Law “On Consumer Lending”, which for the duration of martial law and thirty days afterwards obliges lenders to restructure the debts of certain categories of borrower on their application.
The right belongs to citizens registered as internally displaced people, or who lived in areas of hostilities or temporarily occupied territories. The conditions are strict: the loan must not be secured by a mortgage or a pledge, and there must be no judgment for the debt and no open enforcement proceedings. The application goes to the lender on paper or electronically — in person, by registered post or by email.
The mechanism works like this: the debt is spread in equal monthly instalments over three years, or longer where the original contract provided for it, and the borrower pays the interest within six months of martial law ending. The law separately forbids lenders and debt collectors from taking recovery steps against this category of borrower. If the lender refuses despite every condition being met, a loans and microcredit lawyer can prepare a reasoned demand.
Four options for a borrower in arrears
| Option | Who it suits | Repayment period | Interest and penalties |
|---|---|---|---|
| Agreement with the bank | income has fallen temporarily, the loan was serviced until then | the term is extended by months or years | the bank sets the rate and schedule; part of the penalties is often written off |
| Compulsory restructuring under the Law “On Consumer Lending” | displaced people and residents of areas of hostilities, unsecured loan, no judgment | equal instalments over three years | interest paid within six months of martial law ending |
| Debt restructuring in insolvency proceedings | the debt is objectively unaffordable and there are several creditors | a restructuring plan approved by the commercial court | accrual stops from the day proceedings open |
| Doing nothing | suits nobody | the lender has three years of limitation in which to sue | penalties up to 15 % of the overdue instalment, then court and enforcement |
How to apply for restructuring
- Gather the documents showing your income has fallen: a certificate of dismissal or redundancy, a displaced person’s certificate, a medical certificate, papers about damage to your home. Without written proof the application is just a request.
- Ask the bank for an official statement of the debt broken down into principal, interest, penalties and fees. Compare the penalties charged against the ceiling of 15 % of the overdue instalment.
- Draft the application with a specific proposal: an affordable monthly payment, the term you want, any grace period. A vague “please be understanding” achieves nothing.
- File it so that a trace remains: at a branch with a stamp on your copy, by registered post, or through the bank’s official email address. The filing date is what a complaint will count from.
- Wait for a written answer, and insist on one. A manager’s oral refusal proves nothing to the National Bank or to a court.
- Read the supplemental agreement carefully before signing. Check the new rate, the total cost, whether there is a fee for revising the terms, and whether the accrued penalties have been written off.
What to do if the bank refuses
The first step is a complaint to the National Bank of Ukraine, which maintains the register of debt collection companies and supervises financial consumers’ rights. In parallel, check that the charges are lawful: penalties totalling more than 15 % of the overdue instalment must be recalculated, and the Civil Code expressly forbids raising a fixed rate unilaterally.
Where the debt is genuinely unaffordable and there are several creditors, the court procedure under the Code of Ukraine on Bankruptcy Procedures applies. It opens the way to a restructuring plan approved by the commercial court and, where repayment proves impossible, to writing off the balance. It is a long and costly road with consequences for your assets, so it is not where to start, but personal bankruptcy often turns out to be the only way out for borrowers with several loans in arrears.
Keep the rules on dealing with debt collectors in mind separately. The law allows them to contact a consumer no more than twice a day and forbids it between 20:00 and 9:00, and on weekends and public holidays at their own initiative. A company absent from the National Bank’s register has no right to pursue the debt at all.
Typical mistakes borrowers make
- Stopping payments altogether in the hope of pushing the bank into talks. The effect is the opposite: the case reaches court sooner and the borrower’s position weakens.
- Agreeing orally with a manager and not signing a supplemental agreement. Without a written document the old schedule stands and the arrears keep growing.
- Taking a new loan to close the old one. The debt simply moves into a more expensive form, and one creditor becomes two.
- Signing without working out the total cost. Extending the term by five years cuts the instalment, but the total paid rises noticeably.
- Ignoring court summonses after applying for restructuring. The application does not stop the claim, and judgment will be given without your case being heard.
When you do not need a lawyer
If the arrears are small, the bank itself offered a grace period and the supplemental agreement is clear, sign it yourself: a lawyer would add nothing. The application for compulsory restructuring as a displaced person is likewise filed alone where the conditions are plainly met and the lender agrees. Help is needed where the bank has refused despite a direct statutory duty, where the debt has been inflated by penalties, or where the matter has already reached debt recovery through the courts.
Questions and answers
Must a bank restructure a loan when the client asks?
As a rule no; revising the terms is an agreement between two parties. The duty arises only in the cases the Law “On Consumer Lending” names, in particular for internally displaced people with unsecured loans.
Does restructuring damage a credit history?
Revising the terms looks considerably better in a credit history than arrears. Banks see that the borrower made contact and is still servicing the debt on a new schedule.
What is the maximum penalty on a consumer loan?
Penalties may not exceed twice the National Bank’s discount rate for each day of delay, and in total are capped at 15 % of the overdue instalment. Anything charged above that must be recalculated.
How long does compulsory restructuring for displaced people last?
The debt is spread in equal monthly instalments over three years, unless the contract provided for longer. The interest is paid separately, within six months of martial law ending.
Can a mortgage be restructured?
A revised schedule on a mortgage can be agreed with the bank, but the compulsory restructuring under the Law “On Consumer Lending” does not extend to secured loans. Here the terms depend entirely on negotiation.
When are collectors forbidden to call?
Contact is forbidden between 20:00 and 9:00, and on weekends and public holidays at the lender’s initiative. No more than two interactions a day are allowed, and only companies on the National Bank’s register may act.
What if collectors call my relatives?
Contact with third parties is allowed only with their prior consent given in the prescribed way. Record the breaches and complain to the National Bank; if there are threats, report them to the police.
What does legal help with restructuring cost?
At Svarog a consultation costs from 1,500 UAH, a written legal opinion from 5,000 UAH and pre-action settlement with the bank from 5,000 UAH. The full list is on the page of legal service prices.
Does applying for restructuring stop interest accruing?
No; until the supplemental agreement is signed the old contract applies. Only the opening of insolvency proceedings stops the accrual.
Can the loan currency be changed in restructuring?
That is possible by agreement with the bank and is usually done together with a change of rate and schedule. Work out the total cost at the new rate before signing, since the benefit is not always obvious.
Sources
- Law of Ukraine “On Consumer Lending” No. 1734-VIII — zakon.rada.gov.ua
- Civil Code of Ukraine, Chapter 71 on loans, credit and bank deposits — zakon.rada.gov.ua
- Code of Ukraine on Bankruptcy Procedures No. 2597-VIII — zakon.rada.gov.ua
- National Bank of Ukraine, financial consumers’ rights and the register of debt collection companies — bank.gov.ua
- Law of Ukraine “On the Organisation of the Formation and Circulation of Credit Histories” No. 2704-IV — zakon.rada.gov.ua
Loan restructuring with Svarog
We check the bank’s calculation, prepare the application with a reasoned payment proposal, handle the correspondence with the lender and the complaint to the National Bank, and where necessary run the insolvency case. If collectors are already calling or a copy of a claim has arrived, do not put it off: once judgment is given the options narrow. A consultation costs from 1,500 UAH, and loan restructuring support starts with pre-action settlement from 5,000 UAH.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00