
Олександр Сич
3 April 2026
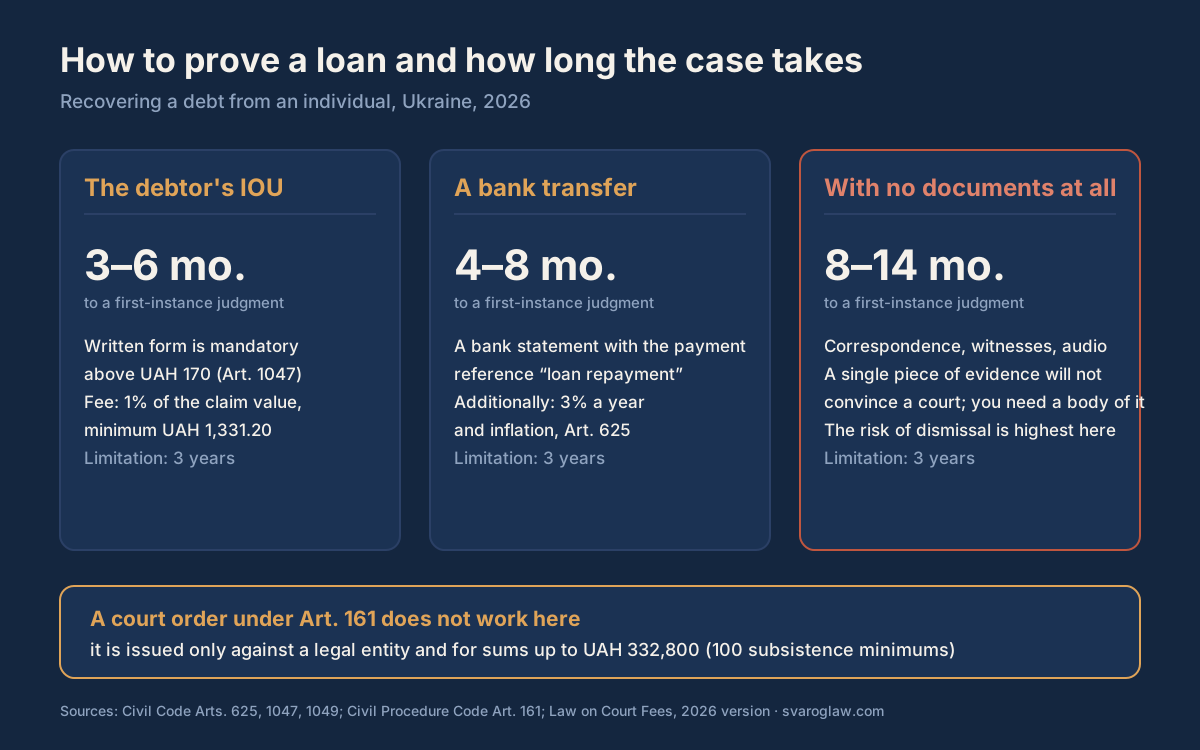
A debt owed by an individual is recovered by ordinary claim: a court order under Article 161 of the Civil Procedure Code is issued only against a legal entity under a written contract for up to 332,800 UAH. The court fee on an individual’s monetary claim is 1 % of the value, from 1,331.20 to 16,640 UAH, and in the Electronic Court it is multiplied by 0.8. The limitation period is three years.
The limitation period, suspended on 2 April 2020 for the duration of the quarantine and martial law, resumed running on 4 September 2025 under Law No. 4434-IX. For anyone who lent money to an acquaintance before the pandemic and kept putting the case off, this means something simple: the three-year period in Article 257 of the Civil Code is running out again, and delay now costs the right to recover at all.
In legal terms a loan between individuals is an ordinary contract, governed by Articles 1046–1053 of the Civil Code. It needs no notary, is entered in no register, and comes into being the moment the money changes hands. The whole difficulty is evidential: the court looks not at how generously you helped, but at whether the documents you have establish the amount, the date and the person who received the money.
When a receipt works and when it is not enough
Article 1047 of the Civil Code requires written form where the loan exceeds ten tax-free minimum incomes, that is 170 UAH. In practice any real loan falls within that requirement, and the borrower’s receipt is sufficient proof of the contract. It should contain the debtor’s full name and passport or tax number details, the amount in figures and in words, the date the money was handed over, and a signature.
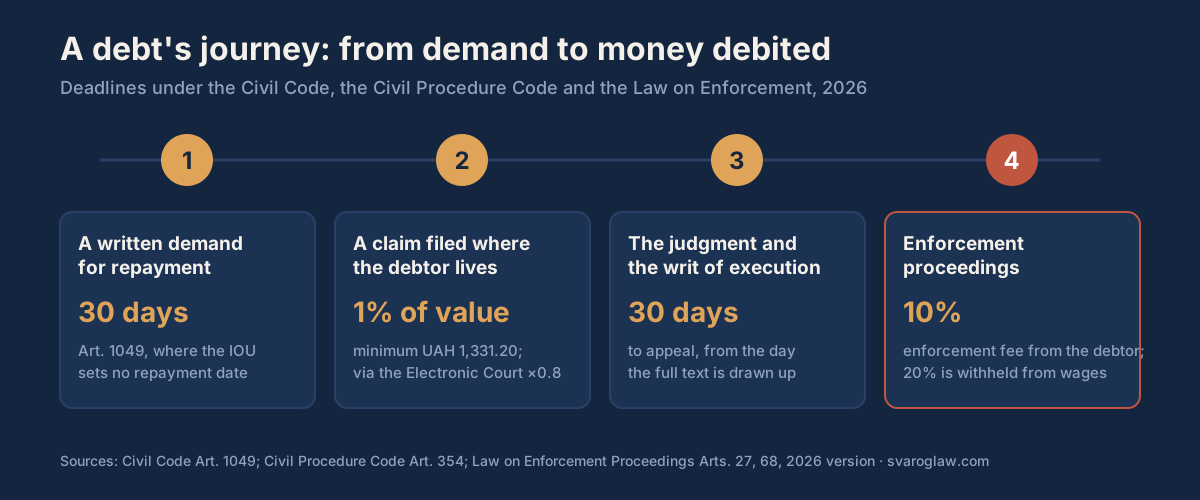
If the receipt does not say when the money is to be returned, that does not make it invalid. Part one of Article 1049 of the Civil Code gives the debtor thirty days from the date a demand for repayment is made, and it is from the end of those thirty days that limitation starts to run. So the written demand is best sent by registered post with a list of contents: the postal receipt becomes the starting point.
The hardest situation is money handed over with no paper at all. Then indirect evidence has to be assembled: a bank statement showing the transfer with its payment reference, messenger correspondence, an audio recording of a conversation, witness statements. Courts accept such evidence, but each item rarely convinces on its own, so only the combination works. We set out the practice of proving a loan without a receipt in detail on the page about recovering a debt under a receipt.
What can be claimed on top of the principal
Most claimants ask only for the sum they lent, and lose money doing so. Article 625 of the Civil Code allows inflation losses for the whole period of default plus three per cent per annum to be added to an overdue monetary debt. Over three years of default that adds a noticeable share to the claim, and the calculation is set out in the statement of claim itself as a separate table.
If the receipt provided for interest on the use of the money, Article 1048 of the Civil Code applies as well. Where the rate is not agreed and the loan exceeds fifty times the tax-free minimum, interest accrues at the National Bank’s discount rate. A loan is treated as interest-free only where the receipt says so expressly, or where the money passed between individuals in a sum not exceeding that threshold and not for business purposes.
Court order or claim: the difference nobody mentions
Online advice often points to a “quick court order”, but for a debt between individuals that route is closed. Article 161 of the Civil Procedure Code allows an order for a debt under a written contract only where the claim is against a legal entity and the sum does not exceed a hundred subsistence minimums for working-age persons, that is 332,800 UAH in 2026. A neighbour’s debt under a receipt does not fall within that list, and the application will be returned.
So what remains is an ordinary claim in the local general court at the debtor’s registered place of residence. If the sum does not exceed a hundred subsistence minimums, the case is heard under simplified claim procedure, which noticeably shortens it. Filing through the Electronic Court is more convenient: documents are submitted with an electronic signature, and the court fee is calculated with a coefficient of 0.8.
| Situation | Main evidence | Realistic time to judgment | Court fee |
|---|---|---|---|
| Receipt with a date and an amount | The original receipt | 3–6 months | 1 % of the claim, minimum 1,331.20 UAH |
| Bank transfer with a payment reference | Bank statement | 4–8 months | 1 % of the claim, minimum 1,331.20 UAH |
| Money handed over with no documents | Correspondence, witnesses, audio | 8–14 months | 1 % of the claim, minimum 1,331.20 UAH |
| A company’s debt under a written contract up to 332,800 UAH | The contract and the acceptance act | 1–2 months | 332.80 UAH for a court order |
What getting your money back costs
Besides the court fee there are legal costs, and they can be shifted onto the debtor: the court apportions costs between the parties in proportion to the claims allowed. To have them awarded, the case file needs the agreement with the lawyer, the act of services rendered and proof of payment, and this must be done before the hearing on the merits ends, or within five days of the judgment if you gave notice of your intention.
At Svarog an oral consultation on the prospects of recovery costs from 1,500 UAH, preparing the statement of claim with the calculation of inflation losses and three per cent per annum from 5,000 UAH, a lawyer’s attendance at one hearing from 3,000 UAH, and handling the enforcement stage from 3,000 UAH. Full handling of a civil case from filing to the money actually arriving starts at 25,000 UAH. The full list is on the legal services price list page.
What to do: from the demand to frozen accounts
- Send a written demand for repayment by registered post with a list of contents. If the receipt sets no deadline, the debtor has thirty days from that moment under Article 1049 of the Civil Code.
- Assemble the evidence: the original receipt, bank statements, screenshots of correspondence showing the phone number or account, written witness statements.
- Calculate the value of the claim: the principal, inflation losses and three per cent per annum for every day of default. The court fee is calculated on that sum.
- File the claim with the court where the debtor is registered, preferably through the Electronic Court with its 0.8 coefficient on the fee. File an application for interim relief freezing property and accounts together with the claim if there is a risk they will be moved.
- Once the judgment is final, obtain the writ of execution and apply to a state or private enforcement officer. The appeal period is thirty days from the date the full text of the judgment is drawn up.
- During enforcement keep the officer’s work under review: check the registers for the debtor’s property, press for accounts to be frozen and for a temporary travel ban.
Enforcement: what is actually recovered
A judgment on its own brings no money. Recovery runs under the Law “On Enforcement Proceedings”, and the officer debits accounts and levies execution against a car, real estate, a share in a company’s capital, and wages. No more than twenty per cent is withheld from earnings, so a debt of several hundred thousand hryvnias takes years to collect from a salary if there is no other property.
On top of the debt the debtor pays an enforcement fee of ten per cent of the sum to be recovered. A private enforcement officer’s basic fee is also ten per cent, but it is collected from the debtor, not from the creditor. The effective lever remains the temporary ban on leaving the country: it is imposed by a court on the officer’s application, and it is what most often makes a debtor suddenly find the money. When a case moves into the enforcement stage we handle it under our debt recovery service.
Typical mistakes
- Threats instead of a demand. Messages along the lines of “pay up or else” get taken to the police, and instead of recovery you face a check under Article 189 of the Criminal Code. A demand should be dry: the sum, the ground, the deadline, and the consequence of a claim.
- A fraud report instead of a claim. Failing to repay a loan is not in itself an offence under Article 190 of the Criminal Code, because intent to take the money must exist at the moment it is received. A refusal to register proceedings is then used by the defendant in the civil case as an argument.
- Letting limitation run out. The court applies the three years only on the defendant’s plea, not of its own motion — but defendants know this. Since 4 September 2025 the period runs normally again.
- Claiming the principal only. Inflation losses and three per cent per annum under Article 625 of the Civil Code are added only if claimed; recovering them later in a separate action takes longer and costs more.
- Pausing after judgment. A writ of execution can be presented within three years, but by then property has usually been signed over. The application to the enforcement officer is best filed in the first weeks after the judgment becomes final.
When you do not need a lawyer
If you hold a receipt with a clear sum, date and passport details, the debtor does not deny the loan and the sum is modest, filing the claim yourself through the Electronic Court is entirely realistic: the form is standard, and in simplified proceedings the court may decide the case without summoning the parties. The application to the enforcement officer is equally manageable alone where the debtor has official employment and a known bank account. Legal help pays for itself where the debt has no written confirmation, where the debtor alleges that no money was ever paid or that the signature is forged, or where the sum is large and property is already being transferred to relatives.
Questions and answers
Can a debt be recovered without a receipt
Yes, but it has to be proved by a combination of indirect evidence: a bank transfer, correspondence, an audio recording, witness statements. Courts treat such evidence as admissible if it shows the sum, the date and the recipient. The claimant’s assertion alone, unsupported, is not enough.
What does filing a claim for 100,000 UAH cost
The court fee is one per cent of the claim, that is 1,000 UAH, but it cannot be less than 1,331.20 UAH. So the minimum rate is what you pay. Through the Electronic Court the sum is multiplied by 0.8 and comes to 1,064.96 UAH.
How long does a debt recovery case take
By law simplified proceedings are heard within sixty days of opening and general proceedings within three months. In practice, allowing for adjournments, repeat summonses to the defendant and an appeal, the period from filing to the writ of execution runs from four months to a year and a half.
What if the debtor has gone abroad
The claim is filed at the last known place of registration in Ukraine, or, if that is unknown, where the defendant’s property is located. Court documents are sent to the registered address, and the person is deemed properly notified. The judgment is then enforced against property and accounts remaining in Ukraine.
Can the debtor’s property be frozen before judgment
Yes, an application for interim relief is filed together with the claim. The court can freeze funds and property up to the value of the claim and decides such an application within two days. The ground is a justified risk that the property will be disposed of, which must be supported — for example by an extract showing a car was recently re-registered.
What percentage is withheld from a debtor’s wages
As a general rule the officer withholds up to twenty per cent of earnings. The figure can be higher for certain categories, maintenance among them, but for an ordinary monetary debt this is the limit.
Are legal fees shifted onto the debtor
Yes, the court apportions costs in proportion to the claims allowed. To obtain reimbursement the case file needs the agreement, the act of services rendered and the payment document. The court may reduce the sum if it finds it disproportionate to the complexity of the case.
Can a debt be sold to debt collectors
The right of claim can be assigned under Articles 512–519 of the Civil Code; the debtor’s consent is not required, they are merely notified in writing. The price of such an assignment is usually well below face value, so it is an option mainly for hopeless debts.
What happens if the debtor declares bankruptcy
Insolvency proceedings for an individual are opened only on the debtor’s own application. Your claim goes into the register of creditors, and repayment follows a restructuring plan or comes from the sale of property. The debt may be written off, so recovering it before the debtor reaches court is the better course.
Sources
- Civil Code of Ukraine, Articles 257, 512–519, 625, 1046–1053 — zakon.rada.gov.ua/laws/show/435-15
- Civil Procedure Code of Ukraine, Articles 161, 164, 274 — zakon.rada.gov.ua/laws/show/1618-15
- Law of Ukraine “On Court Fees” — zakon.rada.gov.ua/laws/show/3674-17
- Law of Ukraine “On Enforcement Proceedings” — zakon.rada.gov.ua/laws/show/1404-19
- Law of Ukraine No. 4434-IX on the resumption of limitation periods — zakon.rada.gov.ua/laws/show/4434-20
- Unified State Register of Debtors — erb.minjust.gov.ua
Recovering a debt with Svarog
We take the case from wherever it stands: we calculate the real value of the claim together with inflation losses and interest, prepare the demand and the claim, secure a freeze on property before judgment, and see the matter through to the money actually being debited in enforcement. Where the documents are thin we start with a consultation and say honestly whether there is a prospect, rather than charging for a hopeless claim.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00