
Олександр Сич
5 April 2026
A notary’s enforcement endorsement is set aside not by complaining to the notarial chamber but by a separate civil claim to declare it unenforceable. The court fee for an individual is 1,331.20 UAH, and enforcement is halted by an interim order, which the court must decide no later than two days after the application arrives.
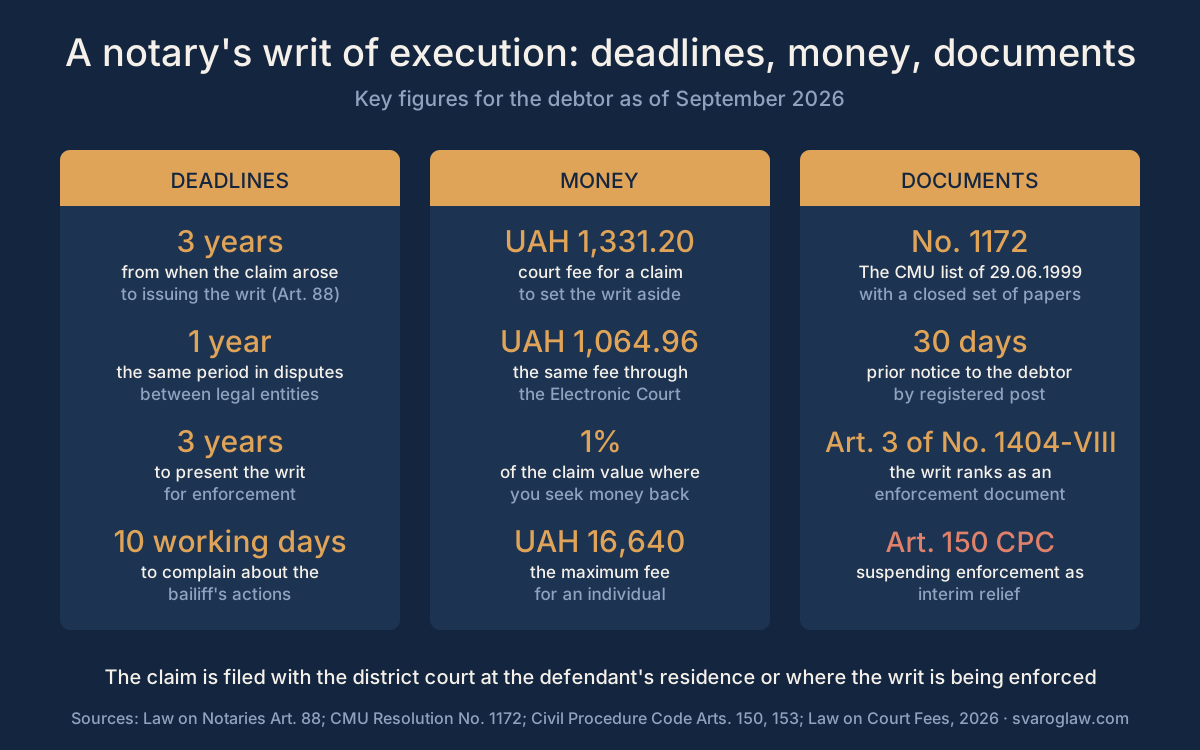
Article 88 of the Law of Ukraine “On Notaries” allows an enforcement endorsement only where the documents filed establish that the debt is undisputed and no more than three years have passed since the right to claim arose — or, between businesses, institutions and organisations, no more than one year. A breach of either condition leaves the endorsement vulnerable in court.
The endorsement suits creditors because it bypasses litigation: within days a notary issues a document that a state or private bailiff treats on a par with a judgment. That is why most debtors learn of an endorsement not from the bank but from a decision attaching their account or their wages.
Why debtors are the last to hear about it
Under paragraph 3 of part 1 of Article 3 of the Law “On Enforcement Proceedings” a notary’s enforcement endorsement is an enforcement document in its own right. The creditor hands it to a bailiff, who opens proceedings, and the debtor receives the decision only once money has been taken from the account or the flat has been attached. The endorsement can be presented for enforcement within three years of being made.
Recent practice shows a steady pattern: banks and companies that have bought portfolios of distressed debt use the endorsement as a fast substitute for litigation. The difficulty is that a notary physically cannot verify whether the sum is disputed if the debtor took no part in the procedure, so the check is in effect shifted to the court in a claim to declare the endorsement unenforceable.
The conditions under which a notary may make an endorsement
The list of documents on which debt is recovered without dispute was approved by Cabinet of Ministers Resolution No. 1172 of 29 June 1999. It is built around types of debt, and for each type a closed set of papers is prescribed. Before making the endorsement the notary must check:
- whether the original of the notarised transaction giving rise to the debt, or a document with the force of an original, has been produced;
- whether the claim falls within the types of debt listed in Resolution No. 1172;
- whether the documents establish that the debt is undisputed and that payment is overdue;
- whether written notice of the debt was sent to the debtor by registered post at least thirty calendar days before the approach to the notary;
- whether the period set by Article 88 of the Law “On Notaries” has expired;
- whether the property sought is property that may be enforced against only by a court order.
Grounds for declaring the endorsement unenforceable
The commonest ground concerns the form of the contract. Consumer loans, credit cards and most microfinance loans are made in simple written form without notarisation, whereas Resolution No. 1172 requires a notarised transaction. Without that notarisation the endorsement was made outside the notary’s powers.
The second ground is the absence of an undisputed debt. Where the debtor disputed the sum in writing, sent a complaint, asked the bank to recalculate or is already litigating over the same contract, the debt ceases to be undisputed and no endorsement may be made. The third ground concerns what the sum is made up of: endorsements often include penalties, fines and fees whose size is itself in dispute.
Deadlines operate separately. Where more than three years passed between the right to claim arising and the approach to the notary, the endorsement falls under Article 88. Bear in mind that limitation, suspended from 2 April 2020, resumed running on 4 September 2025 under Law No. 4434-IX, so the calculations on older contracts need care. Where the debt has already been bought by a debt collection company, it is worth checking the assignment agreement too — work done by our loans and microcredit lawyer.
How to stop enforcement while the case runs
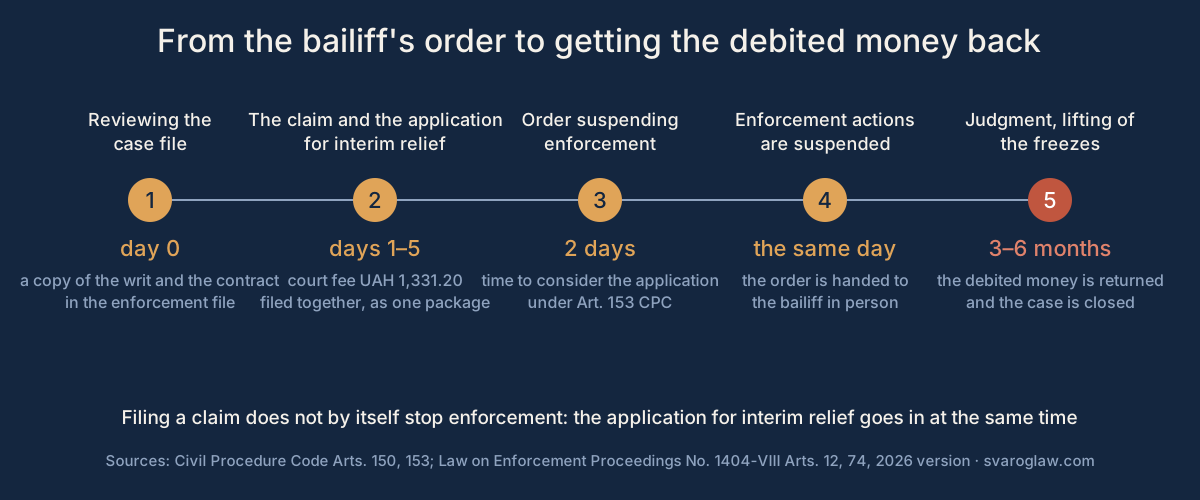
Filing the claim does not by itself stop enforcement, so the application for interim relief must be prepared together with the claim. Paragraph 6 of part 1 of Article 150 of the Civil Procedure Code expressly provides for suspending enforcement under a document the debtor is challenging in court. Article 153 gives the court no more than two days from receipt to decide that application.
The order obtained must go at once to the bailiff running the proceedings, together with an application to suspend enforcement actions. In parallel it is worth checking the lawfulness of the bailiff’s own conduct: their decisions, acts or omissions are challenged in court within ten working days of the person learning that their rights were infringed. If the property is already listed for electronic auction there is no time at all to lose: recovering an object after it is sold is harder than stopping the sale.
What going to court costs
| The debtor’s position | What to file | Timing | Court fee |
|---|---|---|---|
| Proceedings open, nothing taken yet | a claim to declare the endorsement unenforceable plus an application for interim relief | the interim application is decided within two days | 1,331.20 UAH |
| Money already taken from the account or wages | the same claim with a further head seeking the money back | within the three-year limitation period | 1 % of the value of the claim, 1,331.20–16,640 UAH |
| Property or a car listed for auction | the claim plus an application to prohibit the sale of the attached property | file before the auction date | 1,331.20 UAH |
| The endorsement was made more than three years ago | objections to the bailiff and a claim to set aside the endorsement | the endorsement may be enforced within three years | 1,331.20 UAH |
Filing through the Electronic Court subsystem reduces the fee by 20 %, so a non-monetary claim costs 1,064.96 UAH. What a lawyer charges in such cases is on the page of legal service prices: preparing procedural documents from 5,000 UAH, appearing at one hearing from 3,000 UAH, and full court representation from 10,000 UAH.
Step by step: what the debtor should do
- Obtain a copy of the endorsement and of the enforcement file. The debtor is entitled to inspect them at the bailiff’s office, and that is where you will see which contract the endorsement rests on.
- Check the form of the contract and whether notice was given. If the loan agreement was not notarised, or there is no proof that a registered letter went out thirty days in advance, you already have the principal ground.
- Prepare your own calculation of the debt. A difference between your figure and the sum in the endorsement is the simplest way to show the court that the debt is not undisputed.
- File the claim with the district court where the respondent lives or, under part 12 of Article 28, where the endorsement is being enforced. The court fee is paid before filing and the receipt attached.
- File the application for interim relief suspending enforcement at the same time. Two days later, hand the order to the bailiff in person or through the electronic cabinet.
- Once the judgment takes effect, demand that the enforcement proceedings be closed, the attachments lifted and the money returned. The bailiff does this on the strength of the judgment; no separate claim is needed.
Typical mistakes debtors make
- Complaining to the notary or the notarial chamber instead of filing a claim. A notary has no power to set aside their own endorsement, and the time spent corresponding works for the creditor.
- Filing the claim without an application for interim relief. While the court considers the merits, the bailiff quietly sells the property and the subject of the dispute disappears.
- Ignoring letters from the bank and the collectors. It is written objection to the sum that creates the dispute on which the endorsement is later set aside; silence is read as acknowledging the debt.
- Challenging only the bailiff’s attachment decision. Quashing one decision does not deprive the endorsement of force, so the bailiff simply opens proceedings again.
- Missing the deadline to challenge the bailiff’s conduct and relying on the procedural breach later. Ten working days pass quickly, and courts restore that period reluctantly.
When you do not need a lawyer
If you accept the debt, the contract really was notarised, the sum in the endorsement matches your own calculation and the deadlines were met, the court will dismiss the claim and the costs will simply be added to the debt. In that situation it is wiser to negotiate instalments: within enforcement proceedings that is done by an application to the bailiff, and with a bank the conversation is about debt restructuring. A lawyer is needed where the contract is in simple written form, the sum is doubtful, the debt has been bought up, or a flat is at stake.
Questions and answers
Can a notary’s enforcement endorsement be set aside without a court?
No, a notary does not set their own endorsement aside. The only route that works is a claim to declare the endorsement unenforceable, heard by the district court in civil proceedings.
Is an endorsement lawful on a loan agreement that was not notarised?
The list approved by Cabinet Resolution No. 1172 requires the original of a notarised transaction. Where the loan agreement is in simple written form, that is one of the strongest grounds for setting the endorsement aside.
What does filing such a claim cost in 2026?
A non-monetary claim by an individual costs 0.4 of the subsistence minimum for working-age people, that is 1,331.20 UAH. Through the Electronic Court the fee falls by 20 %, to 1,064.96 UAH.
How can money being taken from my card be stopped during the case?
File an application for interim relief seeking suspension of enforcement under the document being challenged. The court decides it within two days, and you hand the order to the bailiff to suspend enforcement action.
How long does a creditor have to present the endorsement to a bailiff?
Three years from the day it was made. If that period has expired and has not been restored, the bailiff must refuse to open enforcement proceedings.
Can money already taken be recovered?
Yes; the claim for the return of money wrongly taken is brought in the same proceedings. That head is monetary, so the fee is 1 % of its value within 1,331.20 to 16,640 UAH.
Does an endorsement reach a debtor’s only home?
Enforcement against a home has its own limits, and some of those questions are for a court alone. Where the flat you live in is involved, the basis and the endorsement itself are worth checking with a property lawyer before the auction begins.
What if the debt was sold to a collection company?
Check the assignment agreement and the scope of the rights transferred. The new company acquires no more than the original creditor had, so every ground for setting the endorsement aside survives.
Will a complaint about the bailiff do instead of a claim?
A complaint removes one decision but leaves the endorsement in force, so enforcement resumes. The two tools work together: the complaint buys time, the claim solves the problem.
How long does a case to set aside an endorsement take?
The first instance usually takes three to six months, depending on the court’s workload. Enforcement can be suspended from the first days if an application for interim relief is filed.
Sources
- Law of Ukraine “On Notaries”, Arts. 87–91 — zakon.rada.gov.ua
- Cabinet of Ministers Resolution No. 1172 of 29.06.1999 approving the list of documents on which debt is recovered without dispute on the basis of notaries’ enforcement endorsements — zakon.rada.gov.ua
- Civil Procedure Code of Ukraine, Arts. 28, 150, 153 — zakon.rada.gov.ua
- Law of Ukraine “On Enforcement Proceedings” No. 1404-VIII, Arts. 3, 12, 74 — zakon.rada.gov.ua
- Law of Ukraine “On Court Fees” No. 3674-VI — zakon.rada.gov.ua
- Unified State Register of Court Decisions — reyestr.court.gov.ua
Setting aside an enforcement endorsement with Svarog
We take on cases where the endorsement is already with a bailiff: obtaining the enforcement file, checking the form of the contract and the notice to the debtor, preparing the claim together with the application to suspend enforcement, and running the case through to the money being returned. If you have just received an attachment decision or heard about an auction, call the same day — the first days decide whether the property can be saved. A consultation costs from 1,500 UAH, and work on debt recovery cases from 10,000 UAH.
+38 095 554-54-24 · Kyiv, 7 Khoriva Street (Podil) · Mon–Fri 9.00–18.00